A message from our partners at Weiss Ratings Dear Reader,
I need to speak with you directly.
I want you to see the most important warning of my career …
And one of the most important warnings any American family will receive before the next great financial crisis hits this country.
I'm Dr. Martin D. Weiss. I'm a Wall Street Journal, BusinessWeek, and New York Times best-selling author.
And for 55 years I have run Weiss Ratings … the only 100% conflict-free, independent financial rating agency in America.
We are paid by no one we rate. We answer to no one but our subscribers.
And in the 55 years since I issued my first public warning before a financial crisis, I have publicly predicted six major American crashes, before they happened.
What I'm seeing now is a $3 trillion problem.
And the biggest danger right now is NOT just another stock market crash.
The biggest danger is NOT only a major bank failure.
Rather, it's a chain reaction of crashes and failures that could cause a global freeze in the financial markets. And it starts here:
Go here now see the most important warning of my career
Good luck and God bless!
Sincerely,
Martin D. Weiss, PhD
Weiss Ratings Founder
11780 US Highway 1,
Palm Beach Gardens, FL 33408-3080
Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list?
Copyright © 2026 Weiss Ratings. All rights reserved.
This Week's Bonus Content Are RTX Corporation and Northrop Grumman Ready to Break Out?Reported by Thomas Hughes. Article Posted: 10/22/2026. 
Key Points- RTX and Northrop Grumman reported record Q3 backlogs and raised earnings guidance, signaling strong long-term revenue visibility despite margin pressures.
- Both companies generated robust free cash flow exceeding $3 billion combined, supporting safe dividend yields and improving balance sheet strength.
- Analysts see high-teens upside for both stocks, with Northrop poised for a stronger recovery after a sharper pullback than RTX.
- Special Report: Elon Musk… A Total Fraud?

Defense stocks RTX (NYSE: RTX) and Northrop Grumman (NYSE: NOC) are facing headwinds, including margin pressures and government scrutiny of their operations. While share buybacks are largely paused amid this scrutiny and the risk of lost contracts, these concerns may already be priced in, shifting attention to the companies' fundamental growth drivers. These include the need to replenish depleted stockpiles, ongoing conflicts and modernization, and increased government spending—all of which point to multiyear cycles for leading defense original equipment manufacturers (OEMs).
Q3 reports in the defense sector revealed record backlogs. RTX, the larger and more diversified of the two, reported $340 billion in backlog, underpinned by a recently awarded Tomahawk missile contract. Northrop’s 1.5x book-to-bill ratio also reflects strong order volume. The takeaway for investors is that these companies have clear visibility into long-term revenue growth and earnings quality, along with the potential to resume or accelerate buybacks next year.
Defense Stocks Outperform in Q3, Raise Guidance, Strengthen Balance Sheets
Larry Benedict went 20 straight years without a losing year. Now he says a major Washington event could trigger a multi-billion-dollar market move as soon as Wednesday, December 9.
Benedict is naming the one three-letter ticker tied to this event free of charge, a strategy once reserved for clients like JPMorgan, UBS, and Bank of New York. Claim Larry Benedict's free ticker pick before Wednesday, December 9 Defense stocks had a decent Q3, with revenue growth in the high-single-digit to low-double-digit range. RTX grew by 11.1%, outpacing its smaller rival by more than 400 basis points, but both companies revealed strengths. Broad-based demand drove growth across commercial and defense applications, with the only weakness being tepid growth in Northrop’s space and missile businesses.
Margins were another strength. Both companies reported strong bottom-line results, outperforming estimates through core improvements and revenue leverage.
More importantly, free cash flow looks robust, totaling more than $3 billion between the two companies—enough to sustain dividend payments while improving balance sheet health. Dividends are the primary form of shareholder return, yielding 1.5% for RTX and 1.8% for Northrop Grumman. They also appear safe, at less than 50% of the earnings outlook.
The earnings outlook is a catalyst for this pair. Both companies raised guidance, lifting their earnings outlooks above consensus estimates. Business momentum is evident and expected to continue for the foreseeable future, underpinning a healthy cash flow outlook despite market misgivings.
These companies can sustain outperformance in this environment, setting the stage for a persistently bullish revision cycle among analysts.
Analysts Praise Defense Stocks, Reaffirm Upside PotentialAnalyst sentiment trends contributed to price corrections for RTX and Northrop in early fall, as price targets softened over the summer. However, those corrections were a market overreaction, leaving the stocks at discounted levels in late October.
The market response to the companies' Q3 results reveals renewed confidence in their long-term growth and profit trajectories, as well as their capital returns. As it stands, both RTX and NOC have high-teens upside to consensus, but offer different opportunities for investors.
While RTX’s correction was more of a pause within an uptrend, leaving it positioned to hit fresh highs, NOC's correction is more of a recovery story—with potential for far more upside. It significantly underperformed its peers during the defense-stock pullback because of company-specific factors. However, Northrop's earnings report rendered concerns such as lost contracts moot by revealing strength in orders and backlog. Its stock looks poised to stage a full recovery.
Balance sheet highlights reflect the strength of these companies' positions: cash positions are strong, assets are growing, debt is falling, and equity is rising. One difference is that Northrop grew equity by 10%, nearly double RTX's pace, while also reducing its share count. Although down significantly from the prior year, Northrop Grumman’s buybacks were enough to reduce its share count while improving equity, providing a dual lever for its share price rebound.
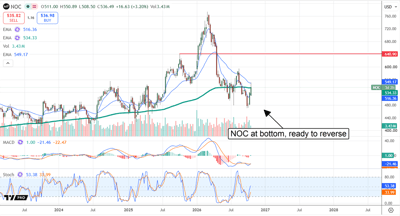
NOC’s share price advanced by 5% following the release, confirming support near $515. The move marks the second of two bottoms, possibly forming a double-bottom reversal pattern, with the potential to reach $595 before year’s end. Other factors supporting the rebound include MACD and stochastic divergences, along with emerging buy signals that point to a strong bottom. The risk is that the market enters a range and remains trapped until more news is available, but this seems unlikely given the trends.
Northrop Grumman’s biggest risk is its exposure to fixed-price contracts such as the B-21 Stealth Bomber. Cost overruns could squeeze margins and weigh on future price action. RTX’s more diversified business is less exposed to this problem; its biggest risks are tied to its commercial business, where cyclicality and lawsuits cloud the outlook. | 