| Unsubscribe |
Quick note.
My new report, The 0DTE Game Plan, normally sells for $29.97 on our website.
But if you use this link today, it costs you nothing.
Inside is a simple 3-step plan for trading same-day options like a business — with your entry, exit and max loss decided before you ever click.
Plain English. No complicated math. Done by the close.
And I don’t sugarcoat the risks, either.
I can’t promise this link will still be free tomorrow. If you’ve been curious about 0DTE, now’s the time.
Click here to claim your free copy before it goes back to $29.97.
Good Trading,
Bill Poulos
p.s. $29.97 normally. Free today with this link.
Alphabet and Unity Level Up Game Development
Author: Jeffrey Neal Johnson. Article Published: 10/9/2026.

Key Points
- Alphabet and Unity announced a partnership on Oct. 7 to build a generative AI gaming platform that lets users create games via text prompts.
- Unity shows signs of a financial turnaround, posting better-than-expected quarterly earnings and 24% revenue growth while leveraging Alphabet's infrastructure to protect margins.
- Roblox faces competitive pressure from the new platform despite its age restrictions, compounded by weak financials and recent insider stock sales by its executives.
- Special Report: Why This Clean Energy Well Escaped the Solar and Wind Cuts.
The economics of game development are undergoing a structural shift. Historically, creating interactive 3D media required specialized coding knowledge or participation in closed, proprietary ecosystems. That dynamic changed on Oct. 7, when Alphabet Inc. (NASDAQ: GOOGL) and Unity Software Inc. (NYSE: U) announced a strategic partnership to build a generative AI gaming platform. By integrating Alphabet's deep-learning models directly into Unity's engine, the alliance will let individual creators generate playable environments with simple text prompts.
This development redefines user acquisition in the application software sector. By removing technical barriers to entry, Unity expands its total addressable market. Alphabet absorbs the significant capital expenditures required to run foundational artificial intelligence (AI) models, allowing Unity to scale its services while protecting its profit margins. As open-architecture tools become more widely accessible, legacy platforms that rely on walled-garden constraints for creators face immediate headwinds.
Spawning the AI-Native Creator Economy
Record Revenue Gold Silver Royalty Firm Still Trades Below 1 Dollar (Ad)
A small-cap gold and silver royalty company is generating record revenue from producing mines, yet shares still trade under 1 dollar.
It just signed the largest transaction in its history, a new gold streaming deal backed by a strategic relationship with a major mining investment firm.
A well-known sector financier has invested his own money and joins the CEO in an exclusive interview breaking down the full story.
Click here for instant access to the free report nowThe Alphabet and Unity partnership will operate in two distinct phases, beginning with a platform called Playground. Available to creators aged 18 and older, Playground allows users to generate and customize playable games using natural language. The system requires no coding background and integrates directly with Google Play Games for immediate access to multiplayer matchmaking, leaderboards and community sharing.
Later this year, the companies plan to introduce Unity Spark, an expansion designed to bridge the gap between text prompts and high-fidelity 3D capabilities. This progression creates a highly calculated user-acquisition funnel. Creators can enter the ecosystem through Playground's accessible interface and eventually scale their projects into professional-grade environments using the established Unity runtime.
This partnership represents a highly efficient allocation of resources. Developing and maintaining generative AI infrastructure demands billions of dollars in specialized computing hardware. Alphabet, with a market capitalization of about $4.23 trillion and net margins near 55%, possesses the balance sheet to absorb those capital expenditures.
Unity gains access to world-class machine-learning models without carrying the infrastructure costs on its own ledger. This advantage allows the company to monetize the resulting software subscriptions and engine fees without draining its internal cash reserves.
Unity Scores High on Margin Protection
This partnership arrives at a clear inflection point for Unity's underlying financials. The developer has historically faced scrutiny over its path to profitability and currently has trailing net income of negative $402.77 million.
Recent earnings data indicate that a pivot is already underway. Unity reported positive earnings of 28 cents per share for the second quarter, beating consensus estimates by 39 cents. Top-line performance also accelerated steadily, with quarterly revenue increasing 24% year over year.
Analysts project forward earnings growth of approximately 96% for Unity. Achieving that level of expansion requires a delicate balance between acquiring new users and controlling operating costs. The Alphabet partnership acts as a catalyst for both metrics.
By leveraging Google's cloud infrastructure, Unity avoids the margin compression that typically accompanies the deployment of native machine-learning tools. The developer can offer a premium, next-generation product suite while keeping its own research and development expenses contained.
Investors evaluating software stocks should look for companies that can expand their user bases without proportionally increasing their debt or operating expenses. Software-as-a-Service models rely heavily on this type of operating leverage to achieve profitability. Unity's strategic alignment with Alphabet fits this criterion, positioning the company to capture a new demographic of nontechnical creators while maintaining a trajectory toward sustained cash-flow generation.
Legacy Moats Take Critical Damage
As generative AI democratizes game development, platforms that rely on closed developer ecosystems face a shifting competitive landscape.
Roblox Corporation (NYSE: RBLX) has long maintained an economic moat by providing accessible creation tools tethered to its proprietary marketplace and player base. However, a direct, AI-powered competitor backed by Alphabet's global distribution network challenges that exclusivity.
While Google's age restriction for Playground protects Roblox's core demographic of younger users in the immediate term, the broader creator pipeline is under threat.
A review of Roblox's balance sheet shows limited financial flexibility to compete with a well-capitalized rival. The company carries an elevated debt-to-equity ratio of 7.82 and generated net income of negative $1.07 billion over the trailing 12 months. Its return on equity is roughly negative 292%, indicating systemic strain in converting shareholder capital into profit. Year to date, Roblox's stock has fallen about 44%.
Corporate behavior deserves additional investor attention during these sector rotations. SEC filings show a pattern of insider distributions ahead of the Alphabet and Unity announcement.
A Roblox director sold 16,666 shares on Oct. 3, while another insider sold 5,666 shares on Oct. 7, the day the partnership was made public. While insider selling can occur for various personal financial reasons, sales coinciding with the launch of a major competitor's product could signal that insiders anticipate future headwinds.
The Endgame for Game Engine Equities
The digital entertainment sector is actively pricing in AI's impact on software development. Companies that successfully integrate generative models into their workflows stand to reduce the time and capital required to bring digital products to market. For investors, tracking how these organizations manage the associated infrastructure costs is essential.
Unity's approach of partnering with a primary cloud provider such as Alphabet Inc. shows a pragmatic way to capture market share without taking on excessive debt. Platforms dependent on proprietary coding languages and siloed user bases may experience increased creator attrition as natural-language tools become more sophisticated.
Investors monitoring the technology sector may want to evaluate application software equities based on their exposure to open-architecture environments. Those looking to capitalize on the democratization of software development could add Unity to their watchlists as the company approaches the launch of the Unity Spark expansion. Cautious investors may prefer to review the upcoming quarterly earnings reports for both Unity and Roblox to confirm whether developer migration trends align with early market reactions.
Rivian Escapes the EV Graveyard—But Can It Stay Alive?
Author: Jeffrey Neal Johnson. Article Published: 10/7/2026.
Key Points
- Rivian's third-quarter deliveries rose about 46% year-over-year to 19,248 vehicles, driven largely by its sub-$50,000 R2 SUV platform.
- A software joint venture with Volkswagen, backed by an initial $1 billion investment, provides a high-margin, non-dilutive liquidity source that offsets Rivian's hardware losses.
- Despite production progress, Rivian faces heavy short interest, continued insider selling, an R2 recall, and a net loss of about $3.65 billion over the trailing 12 months.
- Special Report: Why This Clean Energy Well Escaped the Solar and Wind Cuts.
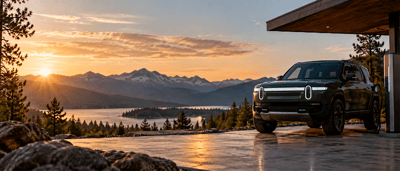
Rivian Automotive (NASDAQ: RIVN) recently reported an approximately 46% year-over-year increase in third-quarter deliveries, indicating that its sub-$50,000 R2 platform is overcoming its early manufacturing hurdles.
Yet beneath this hardware success, a newly formalized software joint venture with Volkswagen Group (OTCMKTS: VWAGY) is quietly providing the liquidity needed to outlast the broader electric vehicle sector shakeout. By emphasizing software revenue and maintaining commercial baseloads, Rivian is building a financial bridge to long-term viability.
Rivian's R2 Delivery Surge
Nvidia pours 7 billion into a light speed AI breakthrough (Ad)
Nvidia has invested more than 7 billion dollars into a light speed device that could reshape how AI systems operate.
Bill Gates put in over 200 million of his own money, while BlackRock, Vanguard, Morgan Stanley and Norway's sovereign wealth fund are positioning around it. Related stocks have already climbed 133 percent, 217 percent and 320 percent.
Wall Street analyst Jason Bodner, who called Nvidia at 4.50, is sharing his top pick tied to this trend at no cost.
Click here to see Jason Bodner's free AI stock pickIn the third quarter of 2026, Rivian delivered a record 19,248 vehicles. This represents an approximate 46% increase from the same period last year, indicating that the company's assembly lines are moving past the bottlenecks that often plague new automotive entrants.
Much of this volume growth stems from the ongoing rollout of the R2 SUV, which has opened Rivian to a broader, more cost-conscious consumer base.
Despite beating delivery estimates, Rivian's stock pulled back slightly after the report. Management held its full-year 2026 guidance steady at approximately 65,000 to 70,000 vehicles rather than raising expectations. This conservative stance reflects prevailing macroeconomic headwinds.
With federal EV tax credits expiring, automakers are relying on promotional financing to move inventory. Keeping guidance unchanged reflects an understanding that, while production challenges are easing, the consumer environment remains tight. For investors, this signals a management team focused on realistic execution rather than inflating short-term expectations.
Volkswagen Backstops the Balance Sheet
Hardware production is notoriously capital-intensive, and Rivian's financials reflect those costs. The company currently carries a trailing 12-month net loss of approximately $3.65 billion and a net margin of about negative 55%.
If Rivian relied solely on selling vehicles and batteries, its cash runway would remain a continuous concern for value-oriented analysts. A current ratio of approximately 2.1 provides near-term breathing room, but long-term survival would require an improvement in unit economics.
However, the financial narrative shifts when factoring in Rivian's joint venture with Volkswagen Group. Volkswagen began deploying an initial $1 billion in capital into Rivian in 2026, creating a non-dilutive liquidity backstop. The partnership centers on Rivian's software architecture, which the legacy German automaker plans to integrate into its global fleets.
This transition alters Rivian's revenue mix. The company's software and services segment recently achieved a gross margin of roughly 42%. By monetizing its software and electrical architecture, Rivian creates a high-margin revenue stream that can help subsidize assembly-floor losses. The joint venture effectively de-risks the balance sheet by providing the capital needed to reach profitability without immediately diluting shareholders. Selling software to other automakers represents a structural pivot that transforms Rivian from a traditional manufacturer into a technology provider.
Anchoring With Amazon Deliveries
Consumer demand for electric vehicles fluctuates with interest rates and general economic sentiment. To insulate itself from these consumer cycles, an automaker needs reliable commercial partners.
Rivian's ongoing fulfillment of electric delivery vans for Amazon (NASDAQ: AMZN) serves as a structural baseload for its factories.
This commercial fleet order provides predictable, contracted volume, allowing Rivian to plan supply-chain purchases and manage factory overhead more efficiently. A more predictable demand curve can also help Rivian negotiate better volume discounts with suppliers and keep costs lower.
While the R2 SUV captures public attention, steady commercial van production helps ensure that Rivian's manufacturing facilities maintain the utilization rates needed to work toward positive gross margins. When the retail market softens, the commercial division acts as a financial shock absorber. This dual-pronged approach gives Rivian an advantage over peers that rely heavily on direct-to-consumer retail sales.
Wall Street's Tug of War
Any stock analysis requires examining where institutional money is positioned. Currently, approximately 154 million shares are sold short, representing about 10.8% of the free float. This indicates meaningful market skepticism about Rivian's path to profitability.
A pattern of insider stock sales reinforces this cautious sentiment. Top executives, including CEO RJ Scaringe and CFO Claire McDonough, sold tens of thousands of shares throughout 2026. While insider selling can reflect standard portfolio diversification or tax planning, sustained selling can be a sufficiently bearish indicator to keep value-oriented investors on the sidelines.
On the operational side, scaling a new model like the R2 is rarely seamless. Rivian recently issued an R2 recall related to improperly tightened battery-pack fasteners. While the issue is not catastrophic, warranty repairs carry near-term costs and pose brand-reputation risks in a highly competitive market.
The options market suggests that speculative capital sees an opportunity to capitalize on the recent price compression. In early October, traders bought more than 147,000 call options in a single session, roughly 27% above the daily average. This activity suggests traders are positioning for upside and weighing the Volkswagen capital injection and production gains more heavily than short-term manufacturing friction.
The Road Ahead for Rivian
The electric vehicle sector has bifurcated. On one side are companies struggling to fund basic operations; on the other are established manufacturers transitioning toward software-defined mobility. As R2 production scales, the high-margin software partnership with Volkswagen subsidizes operations, and Amazon's commercial baseload supports the business. Together, these factors are helping Rivian carve out a position in the latter category.
The transition requires Rivian to navigate steep hardware losses and macroeconomic pressures, but its underlying fundamentals reveal a maturing enterprise. Investors looking to position themselves in the automotive sector may want to evaluate Rivian as it continues to execute on its production targets and integrate its software infrastructure with global partners.
This email message is a sponsored email sent on behalf of Profits Run, a third-party advertiser of DividendStocks.com and MarketBeat.
If you have questions about your newsletter, please email our U.S. based support team at [email protected].
If you no longer wish to receive email from DividendStocks.com, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights reserved.
345 North Reid Place #620, Sioux Falls, SD 57103. United States..