| Unsubscribe |
Jensen Huang said a little-known corner of the AI world is a “once-in-a-generation opportunity.”
As you probably know, he's the CEO of NVIDIA, the top AI chip company in the world.
Strangely, this “once-in-a-generation opportunity” has nothing to do with cutting edge AI chips, programs like ChatGPT, or data center buildouts.
Instead, it involves AI breaking free of computers and the internet to work right beside us in the real world.
And that’s why Jensen Huang also called it "the dawn of a new industrial revolution."
What is he talking about?
See the story, including details on my #1 pick in this exciting space.

NVDA CEO’S “ONCE IN A GENERATION OPPORTUNITY” REVEALED
To your wealth,
Matt McCall
P.S. I called NVDA, back when it was $6. It has shot up 3,100% in 6 years. So, I think NVDA’s CEO knows what he’s talking about. Click here for more details.
A Sub-20 P/E on GOOGL? The Market May Be Missing Something
Submitted by Ryan Hasson. First Published: 9/15/2026.
Key Points
- Alphabet shares rose more than 3% Monday to $349.39, yet the stock's price-to-earnings ratio has fallen to roughly 17.5, below the S&P 500 average.
- Alphabet signed a 22-year power purchase agreement with Fortum for Finland's Loviisa nuclear plant, anchoring a commitment of at least €13 billion in AI infrastructure through 2028.
- Analysts maintain a consensus Buy rating with a $420.19 price target implying 20% upside, while institutions bought nearly $125 billion in shares over the past year.
- Special Report: One Company Spared After Renewable Credits Get Cut.
Alphabet (NASDAQ: GOOGL) made a notable move on Monday, climbing more than 3% to close at $349.39, even as the broader conversation around artificial intelligence turned increasingly cautious over the weekend.
That rally pushed the stock higher, but one number stands out: Alphabet's price-to-earnings ratio (P/E) has fallen below 20, reaching roughly 17.5. For one of the most dominant and profitable technology companies in the world, such a low valuation looks increasingly difficult to justify.
A Rare Discount for a Dominant Business
Jeff Brown Flags a New AI Stock He Compares to Early Nvidia (Ad)
In 2016, Jeff Brown picked Nvidia before it surged 37,800 percent, turning a $5,000 stake into $1,895,000.
Now the Brownstone Research founder points to a small, patented AI technology he calls a 'golden tablet,' claiming it can process intelligence up to 1,000 times faster than standard AI systems.
He says the company behind it is roughly the size Nvidia was a decade ago, with a near-term catalyst arriving November 11.
See the details on Jeff Brown's new AI stock pick nowTo put that multiple in context, the average stock in the S&P 500 trades at a meaningfully higher earnings multiple than Alphabet does right now.
This is a company generating $132 billion in net income, with net margins approaching 55% and a return on equity above 51%.
Businesses of this quality rarely trade at a market discount, yet Alphabet does, with a trailing P/E of 17.5 and a forward multiple near 17. The stock is up a relatively modest 12% this year, lagging several of its mega-cap peers.
Why the AI Slowdown Chatter May Not Be All Bad
Over the weekend, calls for a slowdown in the AI race grew louder, including fresh warnings from prominent researchers about the risks of advancing the technology too quickly. Counterintuitively, that backdrop may not be as negative for Alphabet as it first appears. Google spent the early part of the AI race widely viewed as playing catch-up to OpenAI and, more recently, to fast-moving rivals such as Meta Platforms (NASDAQ: META) and xAI's Grok.
A more measured pace across the industry could actually work in Alphabet's favor, giving it room to close the gap and roll out increasingly competitive models without the pressure of an all-out sprint. For a company with Alphabet's resources, distribution and data advantages, time is often an ally rather than an enemy.
Locking In Power for the Long Haul
Another structural story this month was about electricity rather than algorithms. On Sept. 9, Alphabet announced a 22-year power purchase agreement with Finnish energy company Fortum, securing access to up to half of the output from the Loviisa nuclear plant. The deal anchors a broader commitment to invest at least €13 billion, or roughly $15 billion U.S., in AI infrastructure across Finland through 2028—the company's largest single investment in Europe.
The significance runs deeper than just the headline number, though. Power has arguably become the single biggest bottleneck in the AI buildout, and Alphabet has just locked in clean, reliable baseload electricity for two decades, helping keep a nuclear plant online that might otherwise have closed in 2030. It is Google's first major nuclear deal in Europe and reflects a company thinking years ahead about the constraint that matters most.
GOOGL's Technical Formation Is Taking Shape
On the chart, GOOGL is looking increasingly attractive. After pulling back from its record high set in May, the stock has now spent close to four months consolidating and digesting its prior surge to new highs. Although the stock is now down almost 15% from its 52-week high, it remains above its 200-day simple moving average (SMA) and trades close to several short-term SMAs. As time passes and the range tightens further, GOOGL may be setting up a higher-timeframe bull flag.
Institutional activity and analyst sentiment are also sending positive signals. GOOGL has an outright consensus Buy rating based on 54 analyst ratings. The implied upside based on the consensus price target is particularly notable, with the $420.19 target implying 20% upside potential. In line with analyst sentiment, institutional players have purchased close to $125 billion in stock over the past 12 months, versus almost $74 billion in outflows.
Where Things Stand
Alphabet presents an unusual combination right now: a dominant, profitable business trading at a market discount, paired with a management team making shrewd long-term bets on the infrastructure that will define the next decade of computing. The analyst community remains firmly constructive, and institutions continue to be heavy net buyers. The AI slowdown chatter is worth respecting in the near term, but for investors weighing quality against price, a sub-20 earnings multiple on a company like Alphabet is a setup that rarely lasts long.
Lennar's Q3 Miss Hides a Stronger Operating Story Beneath the Housing Slump
Submitted by Thomas Hughes. First Published: 9/18/2026.
Key Points
- Lennar's Q3 revenue fell 9.2% year over year to $8 billion and missed expectations, while adjusted cash flow dropped sharply to $294 million.
- Despite near-term weakness, Lennar continues aggressive capital returns through dividends and buybacks, supported by a resilient balance sheet with reduced debt.
- Analysts, institutions, and technical signals send mixed but generally supportive signals, suggesting Lennar may be near a bottom ahead of an eventual housing recovery.
- Special Report: One Company Spared After Renewable Credits Get Cut.
Lennar (NYSE: LEN) faces hurdles, but these are near-term issues that obscure what investors should focus on. The company is a cash-flow machine, sustaining aggressive capital returns while building a better business. Key takeaways from the Q3 report and conference call include lower construction costs and faster turnover, which should improve profitability and accelerate growth as the market recovers. Until then, the Even-Flow strategy is working. The company is sustaining volume despite market deterioration by using incentives and gaining share as smaller operators are priced out of business.
Lennar’s capital returns are substantial, even with the risk that they may slow. As it stands, the dividend yields approximately 2.63% with shares trading near long-term lows, while buybacks are aggressively reducing the share count. Shares were down about 7% on average at quarter’s end, giving investors significant leverage and offsetting the impact of buybacks on the balance sheet. Balance-sheet highlights include reduced cash, although the company retains enough to sustain operations and capital returns in upcoming quarters. Total assets remained steady, while debt and liabilities declined. Equity contracted mildly, reflecting the reduction in the share count and the subsequent addition of shares to treasury stock.
Analysts and Institutions Give Mixed Signals - But Support Is Solid
WATCH THIS BEFORE DECEMBER 8th!! (Ad)
James Altucher says a quiet government filing could reveal Elon Musk's biggest move yet, and almost nobody has noticed it.
Altucher believes the filing could matter to as many as 1,806,000 Americans in the years ahead. He explains why Musk buried it and what it could mean, free of charge.
Watch the free breakdown before December 8th to learn moreAnalysts and institutions provide conflicting signals, with a consensus rating of Reduce and reduced activity. However, analysts remain fairly confident, with 19 covering the stock, suggesting that it is an ownable stock, even if September and the Q3 report may not be the right time to get in. Meanwhile, institutional data reflects a reduction in overall activity more than a reduction in total holdings. Trailing 12-month activity shows an approximately $600 million bearish balance, worth about 3.3% of September’s market capitalization, while quarterly activity had declined to less than $100 million as of mid-Q3 2026. Institutions own more than 80% of the stock, reflecting strong confidence in its long-term, cash-generating opportunity.
Short interest is a concern in the near term. It isn’t astronomically high, but it reflects caution and hedging at more than 8%, a long-term high. The risk is that short sellers will lean into the trade and drive the stock to lower lows, although that also creates an opportunity. Trading at 14 times current-year expectations puts LEN stock at the high end of its range, suggesting that lower share prices could lie ahead. The longer-term outlook, however, prices in an eventual housing recovery and puts this stock in the low single digits within five years, suggesting ample upside.
Bears are wrong to assume housing markets will remain frozen forever. While inflation, affordability and interest rates are undercutting demand today, interest rates will eventually fall, unleashing historically high demand. Until then, Lennar’s strategy is focused on building houses to fill the void, using affordability to drive sales and cash flow while honing its process. Looking forward, the company is well-positioned as a top-tier builder, commanding a substantial share of the mid-tier market, the largest segment of housing in America.
Lennar Whiffs in Q3 Despite Structural Improvement
Lennar’s Q3 results highlight the near-term risks. The company’s $8 billion in revenue fell 9.2% year over year and missed expectations because of lower pricing and traffic. New orders also fell 9%, but there was good news: New orders slightly outpaced deliveries, setting the stage for stability, if not growth, in the upcoming quarter.
Other details include reduced earnings power and cash flow. Adjusted cash flow fell by a solid double-digit amount to $294 million, which was insufficient to cover capital returns. That is where the risks lie. In this scenario, the company’s balance sheet can help sustain returns, but it cannot do so forever. The upshot is that Lennar remains in a fortress-like position and can execute its strategy, including taking advantage of ultra-low stock prices. The question is when repurchases may slow and by how much. The answer is likely sometime in the coming year, with buybacks potentially declining by half or more.
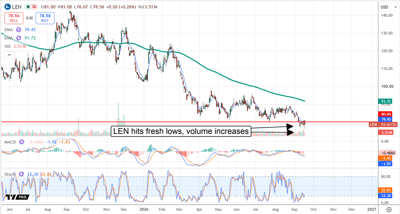
The post-release price action is as mixed as the quarterly details. Results triggered an initial pop, followed by selling and then a rebound, reflecting indecision. The technical signal is a Falling Wedge, which often signals a reversal. The best-case scenario is that Lennar is at its bottom and will begin to recover soon, but it is unlikely to advance significantly and is more likely to re-enter its trading range, which tops out near $90. The worst-case scenario is that Lennar’s support base shifts, begins distributing shares and drives the market to fresh lows, although that is not expected. Factors suggesting that the lows are in include trading volume, which increased as LEN reached its recent lows.
This email communication is a paid advertisement sent on behalf of Monument Traders Alliance, a third-party advertiser of Earnings360 and MarketBeat.
This ad is sent on behalf of The Oxford Club. 105 W Monument St, Baltimore, Maryland 21201. If you would like to optout from receiving offers from The Oxford Club please click here
If you have questions or concerns about your subscription, don't hesitate to contact our U.S. based support team at [email protected].
If you no longer wish to receive email from Earnings360, you can unsubscribe.
Copyright 2006-2026 MarketBeat Media, LLC.
345 North Reid Place #620, Sioux Falls, South Dakota 57103-7078. USA..