| Unsubscribe |
Dear Friend,
Your mortgage rate, your car loan and your savings rest on one assumption: that the world keeps buying American debt.
They stopped.
China held $1.32 trillion of U.S. Treasury debt at the peak. Today, roughly $659 billion. An 18-year low.
That money went into gold.
Beijing's central bank has bought gold 20 months straight, its longest streak in a decade. Goldman Sachs ran the London flows and put China's real buying at 4.8 times the official figure.
And the European Central Bank confirmed what has not been true in generations: gold has overtaken U.S. Treasury bonds as the world's #1 reserve asset. 27% gold. 22% our debt.
The world's most conservative money is not hedging the dollar. It is leaving it.
When foreign buyers stop absorbing our bonds, your rates rise and the interest bill eats the budget. You feel it at the pump and the grocery store.
Washington's counterattack is already signed, funded and filed, with one small American gold company at the center of it.
See Washington's counterattack here >>
"The Buck Stops Here,"
Kelly Maguire
Behind the Markets
Oracle’s Force Majeure Notice Exposes a Bigger Problem for the AI Build-Out
By Thomas Hughes. Article Posted: 9/25/2026.

Key Points
- Oracle issued a force majeure notice tied to its Project Jupiter AI data center in New Mexico due to natural gas pipeline regulatory delays.
- Bloom Energy and Energy Transfer face exposure to the delay, but both retain diversified backlogs and business operations that limit the overall impact.
- Analysts largely maintained Moderate Buy ratings on Oracle, citing accelerating revenue growth and a $664 billion backlog despite the project's near-term risks.
- Special Report: Forget SpaceX. Buy the company Musk can't replace.
Oracle’s (NASDAQ: ORCL) force majeure notice tied to Project Jupiter, its massive AI data center development in New Mexico, is a wake-up call for investors, highlighting the inherent risks of AI’s build-out. Costs are rising, delays are hurting monetization, and bottlenecks are numerous. However, as shocking as the notice may be, it could prove to be more of a long-expected red herring. Force majeure provisions are relatively common in large projects and are used as a defense mechanism. In this case, the notice appears to be a preemptive measure tied to Project Jupiter’s planned 2028 completion.
As it stands, the notice warns that contractual payments could be delayed if the project isn’t completed on time. Oracle is linking its ability to monetize the investment to payments facing headwinds beyond its control. One question is whether the force majeure provision would be upheld in court if the matter ever reached that stage, but that issue may never need to be tested. For now, Oracle says Project Jupiter remains on schedule despite the infrastructure challenges.
Oracle Chokes on Energy Bottleneck: Ripple Effects to Follow?
The REAL Reason Trump is Invading Iran (Ad)
For a moment…
Forget about Trump’s ties to Israel.
Forget about reports of Iran’s nuclear program.
Because my research has led me to believe we’re risking World War 3 with Iran for a completely different reason.
Click here to find out what it is.The bottleneck in question involves energy and, more specifically, regulatory approval for a natural gas pipeline. The pipeline is intended to supply natural gas to the project’s fuel-cell microgrid, with Bloom Energy (NASDAQ: BE) providing the fuel-cell technology. The risk for Bloom Energy is the monetization of its massive backlog, which includes business tied to the New Mexico project.
Delayed construction could delay revenue, cash flow and profits. Worse, it could lead to lost contracts. However, CEOs from the affected companies, including project developer Blue Owl Capital (NYSE: OWL), say they remain fully committed to the build-out. Oracle’s notice is currently a warning rather than evidence that the project has been canceled.
Investors should remember that Bloom Energy has a contractual obligation to Oracle, but its revenue outlook and backlog aren’t tied to a single project. The company has the flexibility to shift production to other projects, whether for Oracle or other customers, and its client base is diverse. A key highlight from its latest report and conference call is that all hyperscalers and most neoclouds have validated the technology, with orders continuing to roll in.
Another company exposed to the potential impact is Energy Transfer, LP (NYSE: ET), the pipeline manufacturer and operator involved in Oracle’s force majeure notice.
However, its stock price took the smallest hit. Energy Transfer’s massive midstream footprint and operational leverage helped offset the delay, making it more of a headache than an existential crisis. Its business is driven by rapidly improving infrastructure globally, industrial demand and the shift toward greener energy sources.
The biggest risk for Energy Transfer and the other companies involved is that the pipeline dispute remains unresolved, preventing the project from crossing a critical 0.6-mile stretch, or that alternative power sources or locations cannot be found. The caveat is that the data centers will ultimately be built; the only questions are whether this particular project will proceed as planned and whether significant delays will emerge elsewhere.

Mixed Reactions Fail to Alter the AI Narrative
Analysts’ mixed reactions focused on Oracle’s pragmatic contractual move as a logical defense in light of the regulatory delays and obvious AI bottlenecks. Ratings and price targets were reaffirmed, with analysts forecasting robust upside for the stock over time. The 40 analysts MarketBeat tracks with current coverage show strong conviction in the Moderate Buy rating, with an 80% Buy-side bias and no Sell ratings logged.
Price target movements were mixed over the summer but still reflected conviction in the consensus, which forecasts approximately 85% upside from the critical support level. The likely outcome is continued volatility for Oracle’s stock in the near to medium term, followed by a move toward the consensus target and potentially higher as its data center projects come online.
Oracle’s risk is the same as everyone else’s: monetizing its AI infrastructure. The project delay is a concern, but it is not the only driver of the stock. The risks are therefore limited, as other projects are in the works and recent results show momentum. Revenue growth accelerated to nearly 30%, underpinned by hypergrowth in cloud segments. Guidance calls for continued acceleration, while the backlog suggests high-level growth for years to come. Oracle’s remaining performance obligation (RPO), a measure of contracted but not yet earned income, rose to $664 billion, or 7.3 times this year’s consensus revenue estimate.
Investors should keep in perspective that Oracle isn’t a technology start-up trying to ramp production to meet anticipated demand. It is an established blue-chip company with the capacity to deliver. Its contracts are not merely memoranda of understanding but firm agreements backed by upfront payments, hardware commitments or both, suggesting that execution is the primary issue. In this scenario, Oracle simply needs to execute its strategy to convert its backlog.

3 Defense Stocks Riding Nuclear, Missile, and Aerospace Demand
Submitted by Nathan Reiff. Published: 9/26/2026.
Key Points
- Rising global defense spending on military modernization and nuclear deterrence creates opportunities for both large and small defense-related companies.
- BWX Technologies and Mercury Systems both reported strong backlog growth and raised guidance, reflecting robust demand for their specialized defense niches.
- Howmet Aerospace continues posting strong revenue growth and pursuing acquisitions despite facing new competition from GE Aerospace's purchase of a rival supplier.
- Special Report: Forget SpaceX. Buy the company Musk can't replace.
The United States and other governments around the world are prioritizing military modernization, building their nuclear deterrence capabilities, enhancing missile defenses and investing heavily in defense. This shift toward a more militarized world may give investors opportunities to capitalize on both large defense contractors and smaller companies with significant growth potential.
When seeking meaningful returns in the defense sector, investors may want to look for companies with unique technological niches, distinct positions within the defense supply chain and signs of business momentum, such as significant operational updates. BWX Technologies Inc. (NYSE: BWXT), Mercury Systems Inc. (NASDAQ: MRCY) and Howmet Aerospace Inc. (NYSE: HWM) may all be appealing candidates for these reasons.
BWX Finds a Lucrative Niche in Nuclear Propulsion
A letter from Shannon Stansberry (Ad)
Porter Stansberry nearly canceled the entire project. When he first saw the claimed returns - only one down year in nearly two decades and total gains of almost 2,000% - his immediate reaction was disbelief.
It took a trusted friend's personal vouching for Emmet Savage and a face-to-face trip to Ireland to change his mind. The full documentary, Investigating Project Prophet, is now live.
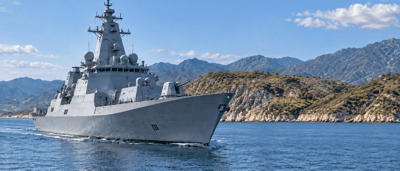
Watch the full story and see the verified track record for yourselfBWX is a nuclear component maker that serves the nuclear energy market, medical customers and the U.S. government. In particular, its work designing nuclear reactors and components for naval vessels has made it a major player in the U.S. Navy's nuclear propulsion program.
This has led to noteworthy demand and a substantial backlog, which climbed 40% year over year (YOY) to $8.4 billion in the latest quarter.
BWX's relationship with the U.S. Navy has also boosted its top and bottom lines. Q2 2026 revenue climbed 18% to about $902 million, just shy of analyst estimates, while adjusted EBITDA and adjusted earnings per share (EPS) also increased YOY. Company leadership raised its full-year guidance in response.
There's reason to believe this momentum could continue and may reverse BWXT stock's downward performance trend (shares have fallen about 20% so far in 2026). Over the summer, the company secured a contract with the National Nuclear Security Administration to develop a new lithium-processing facility.
Additionally, BWX is narrowing its focus by selling its medical business for up to $800 million. The transaction would provide a substantial boost to its capital reserves while allowing the company to prioritize its highest-potential operations.
Mercury's Financials Continue to Improve as Defense Moves Toward Software
Mercury's role in the defense industry is different. The company provides secure processing hardware, computer equipment, sensors and other subsystems for aircraft, missiles and radar systems. As the defense industry increasingly adopts software and electronics, Mercury may have an increasingly important role to play.
Like BWX, Mercury reported impressive bookings and backlog in its latest quarter. Bookings rose 93% YOY to $660 million, while backlog approached $2 billion. The company also raised its forward guidance and now expects fiscal 2027 revenue to reach nearly $1.1 billion.
Mercury is improving its margins, with its adjusted EBITDA margin climbing 217 basis points last quarter to 15.3%.
Shares of MRCY have performed differently from BWXT stock, rising about 14% year to date (YTD) despite shedding approximately 7% over the past month. If the company can continue addressing manufacturing inefficiencies while maintaining strong, high-quality revenue growth, it may better justify analysts' optimistic views of the stock, including expectations for about 33% in potential upside.
Howmet Holds Its Own Against GE
Perhaps best known for its engineered components for commercial aerospace applications, Howmet is also continuing to expand its offerings for the defense sector.
The company may present a buy-the-dip opportunity for investors following news that GE Aerospace (NYSE: GE) would spend $12 billion to acquire Consolidated Precision Products, a rival aerospace component maker. While the deal appears to threaten Howmet's share of the customer base, significant capacity shortages across the industry may allow both companies to benefit from strong demand for years to come.
Even after a recent 13% dip over the past month, HWM stock remains up 12% YTD, suggesting that investors see strength in the company's operations and financials. In the last quarter, that strength was reflected in strong top- and bottom-line results that exceeded analyst expectations, including 24% YOY revenue growth driven by broad-based demand.
Howmet also benefits from data center demand, which has driven interest in its gas turbines. The company is pursuing consolidation as well. Like GE, Howmet made a major acquisition earlier this year of Consolidated Aerospace Manufacturing, expanding both its manufacturing capacity and product offerings. Howmet could continue to benefit from the essential nature of the products it provides for commercial and military aircraft.
This email communication is a paid sponsorship sent on behalf of Behind the Markets, a third-party advertiser of MarketBeat. Why was I sent this email content?.
If you need help with your account, feel free to email MarketBeat's U.S. based support team at [email protected].
If you would no longer like to receive promotional emails from MarketBeat advertisers, you can unsubscribe or manage your mailing preferences here.
© 2006-2026 MarketBeat Media, LLC.
345 N Reid Place, Sixth Floor, Sioux Falls, S.D. 57103-7078. USA..