Hello,
Welcome to our flagship newsletter, MarketBeat Daily Ratings.
We'll deliver the latest "Buy" and "Sell" ratings from Wall Street's top-rated analysts directly to your inbox each morning.
But first, we need you to do two quick things:
1. Hit reply, and send a simple "Yes." Just one word. This tells Google (and other emails providers) that you actually want to get our newsletter.
2. After that, this link to confirm your subscription. That will tell us that you received our welcome email and that we should start sending your daily report.
Confirm your subscription here.
After you have completed these two steps, we would like to gift you a free copy of one of our most popular investing reports: 7 Stocks to Buy and Hold Forever. You can download the report with this link.
Thank you again for subscribing. We look forward to being an important part of your investing journey
Matthew Paulson
Founder and CEO, MarketBeat.
P.S. If you didn’t intend to subscribe, no problem—you can unsubscribe with this link.
(ARReply-161)
This Week's Featured Article The Fed’s Rate Hike Could Backfire If Oil Prices CollapseSubmitted by Thomas Hughes. Date Posted: 9/17/2026. 
Key Points- The FOMC hiked rates in September for the first time in over three years, with another hike likely later this year despite risks to economic growth.
- Oil markets are in backwardation, signaling expectations that prices could fall roughly $40 by year's end or early 2027 as demand destruction and rising supply take hold.
- Structural risks, including Russian refining capacity losses from the Ukraine war, could keep crack spreads and consumer prices elevated even if crude oil prices decline.
- Special Report: Forget SpaceX. Buy the company Musk can't replace.
The FOMC confirmed market fears and hiked rates in September, marking the first hike in more than three years. While another hike looks likely this year, investors should consider the duration of this cycle before making major moves.
As concerning as inflation is, much of the current pressure is being driven by high oil prices, which can reverse quickly. High today, prices could fall at the drop of a hat. The FOMC has no real control over oil prices, only demand—and that, by proxy. Hiking rates may curb demand and ease inflation, but it could also undermine economic activity, risking a contraction or stagnation.
Silver is up more than 50 percent over the past year, yet interest has faded since its January record.
The metal gave back roughly half that move and most traders moved on to other trades.
One explorer kept its drill rig running through the pullback, working the site while attention was elsewhere. See what this silver explorer has been drilling for Hiking rates now—and hiking aggressively—only puts the economy at risk when additional risk is the last thing it needs. As it stands, inflation is running in the mid-3% range, well above target. The risk is that inflation falls faster than anticipated, dropping below 2% and into the anemic range, with U.S. expansion reverting to zero or even contracting.
In this scenario, the Fed will follow up its hike with a cut, potentially bringing rates back to nearly zero as it tries to reinvigorate economic expansion. Meanwhile, the aforementioned structural forces in the oil market could quickly undermine inflation through a drop in prices that is all too likely.
Oil Futures Signal a Sharp Price Drop as Demand Shifts
Oil markets run on futures. Some companies buy spot oil as they need it, but not many do. Most producers sell future production, while consumers hedge their positions to offset costs. Futures contracts typically become more expensive the farther they are from expiration at the same strike price. This pricing covers storage and other costs, including implied volatility, but that is not the case today.
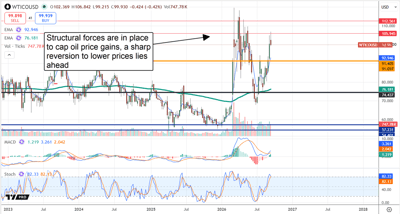
Today, the oil market is in backwardation—longer-dated oil contracts are less expensive than near-term contracts, revealing a market that expects prices to drop. The curve is highly suggestive, implying a decline of as much as $40 by year-end or early 2027, which would put WTI in the mid-to-low $60s and Brent in the mid-$70s.
What is the market looking at? Demand destruction compounded by rapid market normalization. The International Energy Agency says higher prices are forcing businesses and industries to seek alternative energy sources and move away from oil faster than expected. Notable industries turning to alternative sources include hyperscale data centers, which are relying on natural gas, catalytic fuel cells from Bloom Energy (NASDAQ: BE), and nuclear power. In addition, the transition to electric vehicles continues to progress, undermining demand, while natural gas gains share as an industrial power source.
Natural gas is attractive for many reasons, including its efficiency and cost. It is the cleanest-burning fossil fuel and costs about 80% to 85% less than crude oil per British thermal unit (BTU). Its growth is also supported by rapidly expanding capacity along the Gulf of Mexico, enabling exports to international markets. Internationally, natural gas demand is underpinned by rapidly improving infrastructure that enables product to flow where it is needed.
Oil Oversupply Looms as Refining Risks Keep Prices Elevated
No one really knows when the Strait of Hormuz will reopen, but it is unlikely to remain closed forever. The economic strain on directly affected nations will lead to some resolution sooner or later. When that happens, oil prices will quickly revert to the low end of their range. Until then, any good news will be a catalyst for selling, and other risks to oil prices remain.
Non-OPEC production, including domestic production, Guyana and Brazil, as well as potentially soon Venezuela, is ramping up to help offset supplies constrained by disruptions at Hormuz and in the Red Sea. The key takeaway is that demand destruction and rapidly rising supply will lead to a massive oversupply, which is forecast for next year.
And the oil charts suggest this move is being priced in. WTI shows resistance at $105, well below the existing highs and at the low end of the target range. A move higher is still possible, but unlikely without another capacity blow. Higher interest rates are also bearish for oil, setting the stage for this to become a self-fulfilling prophecy. Higher rates strengthen the dollar, which is negative for oil prices because oil is priced in dollars—the stronger the dollar, the fewer dollars it takes to buy the same barrel.
The biggest risk for oil isn’t so much capacity or production as refining. The war in Ukraine is knocking out Russian refining capacity, which is vital to the world. Russia accounts for about 6.5% of global refining capacity and is a top-10 refiner, but it focuses on diesel. Russia accounts for more than 10% of global diesel refining capacity, ranking second behind the U.S.
In this scenario, distillates are the bigger issue and will likely keep crack spreads and consumer prices high, regardless of oil supplies or the situation at the Strait. Ironically, the war in Ukraine also emerges as a factor in demand destruction: It is being fought in the air, by drones, with batteries and joysticks. Another irony is that raising the cost of doing business through higher rates will increase inflation in the near term, before rates have their intended effect. |