Hello,
Welcome to our flagship newsletter, MarketBeat Daily Ratings.
We'll deliver the latest "Buy" and "Sell" ratings from Wall Street's top-rated analysts directly to your inbox each morning.
But first, we need you to do two quick things:
1. Hit reply, and send a simple "Yes." Just one word. This tells Google (and other emails providers) that you actually want to get our newsletter.
2. After that, this link to confirm your subscription. That will tell us that you received our welcome email and that we should start sending your daily report.
Confirm your subscription here.
After you have completed these two steps, we would like to gift you a free copy of one of our most popular investing reports: 7 Stocks to Buy and Hold Forever. You can download the report with this link.
Thank you again for subscribing. We look forward to being an important part of your investing journey
Matthew Paulson
Founder and CEO, MarketBeat.
P.S. If you didn’t intend to subscribe, no problem—you can unsubscribe with this link.
(ARReply-161)
Today's Bonus News Roper Technologies In Rebound and a Hot Buy Despite Insider SellingAuthored by Thomas Hughes. Posted: 9/9/2026. 
Key Points- Roper insiders sold shares near depressed summer levels, but the company’s Q2 results and guidance increase point to stronger fundamentals.
- Roper’s niche software businesses, AI product development and recurring revenue profile help counter broader SaaS disruption fears.
- Buybacks, dividend growth and expected Indicor proceeds support the capital-return case, though acquisitions and integration remain key risks.
- Special Report: Everyone wanted SpaceX. Smart money wants this.
Roper Technologies (NASDAQ: ROP) insiders raised eyebrows over the summer by selling shares near long-term lows. The move ran counter to the fundamental signals in the Q2 earnings report, which suggested deep value and the potential for a rebound that has since begun.
The takeaway for investors is that insider activity isn’t always the signal that headlines make it out to be, and investors should consider other factors before making investment decisions. In this case, insider sales are a red herring that distracts the market from an otherwise bullish opportunity.
Roper Technologies Is Immune to SaaS-Pocalypse Disruption
Silver is up more than 50 percent over the past year, yet interest has faded since its January record.
The metal gave back roughly half that move and most traders moved on to other trades.
One explorer kept its drill rig running through the pullback, working the site while attention was elsewhere. See what this silver explorer has been drilling for Roper Technologies is the holding company for a diversified portfolio of application and network software businesses, as well as technology-related manufacturers. The 2026 narrative is that its stock price imploded because of SaaS-Pocalypse fears that have since proved unfounded. Roper Technologies has a sizeable moat, providing critical niche software for heavily regulated industries, including healthcare and insurance.
While AI model developers or customers’ internal efforts could disrupt its business, Roper is well established in industries where switching vendors after implementation is difficult, at best. Roper’s advantage lies in its ability to deliver AI functionality through its existing framework, enabling faster time to market and lower costs for customers.
Highlights from H2 2026 include persistent outperformance, continued growth and improving guidance. The company raised guidance at the end of both quarters, signaling improving momentum and a likely continuation into the second half of the year. Key highlights include accelerating earnings growth and ample cash flow to support robust buybacks. Executives took advantage of improved cash flow and low share prices to repurchase shares aggressively, reducing the share count by 8% over the trailing three quarters.
Roper Technologies Is Well-Positioned for Capital Returns
The only bad news is that aggressive share repurchases increased debt and reduced equity at the end of Q2. However, there is an offset: One of its portfolio companies sold an asset expected to generate more than $1.25 billion in cash for Roper Technologies. The company plans to use that cash to strengthen its balance sheet and prepare for future acquisitions. Even so, the balance sheet remains healthy, with total liabilities below 1x equity, net long-term debt just above 0.5x equity, and liabilities below 0.5x assets. The likely outcome is that Roper will continue generating cash, enabling it to execute its strategy, including acquisitions and capital returns.
Capital return includes dividends. The dividend isn’t substantial, yielding about 0.8% with shares well off their highs, but it is reliable, and distributions are expected to grow annually. The company pays less than 20% of its adjusted earnings outlook and has increased its payment annually for more than three decades. In this scenario, the stock is a Dividend Champion on track to become a Dividend King, as reflected in analyst and institutional activity.
Analysts and Institutions Underpin Support and Drive Price Rebound
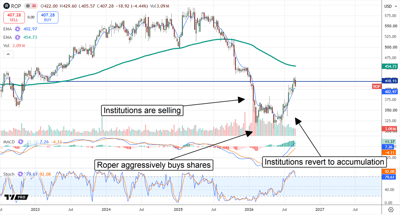
Analyst data shows relatively firm conviction in the stock, with 19 analysts tracked. They rate ROP as a Hold, with only three sells logged and an approximately 37% buy-side bias. Activity was mixed following the Q2 release in July, including some downgrades and price-target reductions, but it also included numerous upgrades and price-target increases. The activity ultimately affirmed the Hold rating and consensus price target of $466. That implies roughly 15% upside as of early September, while many individual targets are substantially higher.
Institutional activity is more bullish, with institutions owning more than 90% of the stock and accumulating shares aggressively in early Q3. InsiderTrades data shows selling in Q1 and Q2 but a return to accumulation in Q3, with activity surging to a multiyear high in line with the stock price rebound.
Stock price action suggests the stock topped in September. ROP moved above $418 for the first time since early January, triggering a selling event. The price action confirmed resistance at a critical target, setting the stage for an inflection later this year. The stock may pull back as deeply as $375 before making another attempt at fresh highs, but new highs are likely given the company’s growth, outperformance and capital returns. Assuming a move to fresh highs, the technical targets match the magnitude of the reversal pattern—about $100—indicating a move toward the $518 region within two to three quarters.
The company’s biggest risk is acquisition integration. Because it focuses on earlier-stage companies, it faces a higher risk of missteps and delays. However, its solid track record somewhat mitigates that risk. Roper focuses on high-margin, asset-light businesses within its target verticals. Rather than rushing into integration, the company tends to leave existing management in place, allowing acquired businesses to grow independently while Roper explores synergies and other opportunities. |