| Unsubscribe |
Dear Reader,
Most AI stocks can tell a great story.
One hidden company can point to $100 million in quarterly Robotics revenue.
The same business has posted five consecutive quarters of sequential growth. Robotics revenue also rose 33.4% from the year-earlier period.
And on September 14, its robotics operation introduced a new platform built to move physical AI from the lab into industrial operations.
The launch has happened. The revenue trend is already in motion. Yet most investors still do not know the stock.
See why I believe physical AI could survive the coming split by clicking here.
I'm Matt McCall, a former Fox Business host who called the 2009 market bottom and later recommended Nvidia at around $6 a share. My research has also identified 51 investments that went on to rise at least 1,000%.
I mention that because the pattern in front of us feels familiar: a real technological revolution surrounded by companies whose prices may be running far ahead of their economics.
On one side: expensive promises, crowded trades and three hyped names I believe investors should avoid.
On the other: physical-AI businesses already building machines, winning customers and producing measurable revenue.
Learn about why I believe AI is splitting between hype and real-world utility for free.
The concealed company owns the business described in my research as the world leader in collaborative robots, with a cited 31% share of the cobot market.
Amazon provides the customer-side proof. Its Vulcan robot can use touch to pick and stow goods, and the company in my research supplies an important component.
The source analysis estimates a roughly $400 million revenue opportunity if Amazon's plan unfolds as expected — enough to more than double the company's prior-year robotics revenue.
Nvidia provides the technology-side proof through its Isaac robotics platform.
The market will not announce when it separates productive AI from hype. By then, vulnerable names may already be falling.
That is why I put together my Great AI Shock presentation now.
To your wealth,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. The most important part may be recognizing the split before it becomes obvious.
Learn more about the warning signs before it is too late.
Why Guidewire’s Post-Earnings Plunge May Not Last
Author: Thomas Hughes. Date Posted: 9/7/2026.

Key Points
- Guidewire shares fell after the company issued cautious guidance tied to its shift from legacy licensing to cloud-based subscription revenue.
- Despite the guidance-driven selloff, Guidewire posted 15% revenue growth, expanding margins, and 51.4% year-over-year operating income growth last quarter.
- Analysts remained bullish overall, with no downgrades, a consensus price target near $220, and continued institutional buying supporting a potential rebound.
- Special Report: The company SpaceX cannot operate without
Guidewire Software’s (NYSE: GWRE) post-release stock plunge looks like a knee-jerk reaction that could soon reverse.
The plunge was caused by tepid guidance tied to a strategic shift from legacy licensing models to cloud-based subscriptions. Although the subscription model generates less revenue initially, it produces higher margins. The near-term downside is slower top-line growth, but sluggish growth in the face of expanding margins creates an opportunity to improve both.
If you keep cash in a U.S. bank account… read this NOW (Ad)
Since 2020, U.S. banks have been required to keep zero percent of deposits on hand, lending out nearly every dollar while paying savers just 0.04 percent interest.
A new law, the GENIUS Act signed last summer, has cleared the way for a different kind of money to emerge this fall, one that could offer savings rates up to 6 percent.
See what Ian King, Chief Strategist at Strategic Fortunes, has uncovered about this shift before it goes live.
Click here to see what Ian King found about this new savings shiftAs it stands, the cloud transition underpins a robust outlook, and its near-term drag on revenue is widely expected to fade. The more important story is what the transition is now producing: accelerating recurring-revenue growth and improving profitability.
Adjusted net income grew only 300 basis points faster than revenue, partly because of increased investment. Operating income grew more substantially, rising 51.4% year over year (YOY) and pointing to ample cash-flow and capital-return capacity over time.
Guidewire Outperforms, Issues Cautious Guidance
Guidewire had a solid quarter despite the impacts of its strategic shift. Revenue grew 15%, outperforming estimates by 200 basis points (bps), driven by a 32% increase in subscriptions and a 10% increase in services. Licensing, the legacy business, contracted 18% and is expected to continue declining in the coming quarters. Cloud annual recurring revenue (ARR), a measure of annual subscription-based sales, grew 35% to account for 84% of total ARR, providing visibility into future results and suggesting that cloud-based revenue growth will accelerate.
Margins were the quarter’s bright spot, improving across comparisons and bringing adjusted earnings to 99 cents per share, up 22% YOY and 5 cents ahead of consensus. The only downside was the impact of capital expenditures (CapEx) and investments, which reduced bottom-line strength.
Cash flow is sufficient to sustain the fortress-like balance sheet while returning capital to shareholders. Capital returns include aggressive share buybacks, which reduced the share count by 3% YOY as of fiscal Q4 and are expected to continue in future quarters.
The immediate headwind is that the Q1 forecast came in below expectations, but a catalyst for share-price recovery is already in play. Guidance is likely to remain cautious, given the company’s cloud strengths and signals from other AI-enabled, cloud-based software providers that collectively point to accelerating demand across the software ecosystem. In this scenario, Guidewire could outperform next quarter, prompting an upward revision to its already-strong full-year guidance.
Analysts Respond With Caution, Outlook Remains Bullish
The primary takeaway from analysts' responses to the release was caution centered on the tepid revenue outlook. No downgrades were issued, but numerous price targets were reduced, limiting the upside potential while reinforcing the consensus view. Consensus, as reported by MarketBeat, is pegged in the low $220s, indicating 10% upside relative to the pre-release close and nearly 35% upside following the release. GWRE stock is likely to remain under pressure over the coming months, with no significant catalyst for a rebound expected until the Q1 results are released.

Technically, GWRE stock is in the midst of a major reversal, and the post-release plunge aligns with that trend. Price action reached fresh long-term highs earlier this year, breaking above several resistance targets, including a cluster of moving averages that now form a Golden Cross. As of early September, GWRE has retreated to a pivot point to retest support, which is likely to hold.
Institutional activity was bullish ahead of the release and is likely to remain so afterward. Although selling capped gains earlier in the year, the group returned to an accumulative posture in early Q3, helping drive the stock through its resistance targets. The likely outcome is that this group buys the dip, potentially accelerating accumulation because of the steep discount.
High Valuation Versus Deep Moat and Visibility
Guidewire’s biggest risk is its valuation. The stock traded at about 50 times earnings ahead of the report, setting the stage for execution-related volatility that the weak guidance triggered. Investors may be getting it wrong, however. Near-term headwinds are easing, while the long-term outlook includes improving margins, cash flow and capital returns, supported by the company’s ever-deepening moat.
Guidewire is a mission-critical software layer for insurance companies globally, providing operating systems for more than 500 insurers and counting. The platform is indispensable to their operations and incredibly costly to replace because it affects 100% of their business. A clear sign of strength is the nearly 100% retention rate, signaling that once onboarded, an insurer is likely to remain a customer for life. The company also has an underappreciated growth driver tied to insurance inflation: Guidewire’s network earns a toll as inflation increases costs and natural disasters drive activity.
Can Bloom Energy Pop the Top Off AI’s Massive Energy Bottleneck?
Author: Thomas Hughes. Date Posted: 9/21/2026.
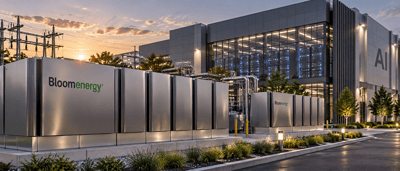
Key Points
- Bloom Energy benefits from surging AI power demand because its fuel cells can be deployed within months, far faster than new grid capacity.
- The company ended 2025 with about $20 billion in backlog, growing hyperscaler approvals, and expanding financing partnerships, including a $25 billion Brookfield framework.
- Analysts maintain a Moderate Buy rating with rising price targets, though a scandium oxide supply dispute with short-sellers remains a risk to monitor.
- Special Report: The company SpaceX cannot operate without
AI’s energy bottleneck is real.
With a single GPU consuming as much power as an average kitchen appliance and requiring continuous operation, the electricity needed to run AI applications and drive their advancement is staggering.
This Nasdaq drone company just landed a Pentagon defense contract (Ad)
One Nasdaq-listed drone company already supplies the US Army, Air Force, and Navy with mission-ready drone systems for reconnaissance and tactical operations.
Now, alongside F4 Defense International, it has been selected by the Department of War to build a next-generation counter-drone system that detects, tracks, and defeats hostile drones. The company is also integrating Palladyne AI's SwarmOS platform for autonomous swarm intelligence, with commercial clients including Shell, Ford, and Red Bull.
See why US defense agencies are turning to this drone companySmall research labs may use two to eight nodes, or as many as 64 GPUs, on average. Enterprise capacity requires exponentially more, and the power drain only increases as you move up the stack to tier-two hyperscalers, the neoclouds, hyperscalers, and frontier AI labs.
AI data-center expansion is increasingly constrained by U.S. power availability, grid interconnection delays, and equipment shortages. Estimates suggest data centers could consume 9% to 17% of U.S. electricity by 2030. This is a problem that isn’t going away—it’s only going to get worse over time.
Power-generation capacity is insufficient, the grid can’t handle the loads, and improvements take a long time. At the low end, equipment lead times are about six months; at the high end, they can extend for years. The AI industry needs power today.
Energy is no longer just a bill to pay; it is a major infrastructure hurdle to factor into capital expenditures (CapEx). That’s why AI infrastructure companies have committed more than half a trillion dollars, signaling a massive shift in the industry’s dynamics.
To circumvent the five- to seven-year timeline for new grid capacity, companies have adopted several strategies, including co-locating campuses near power-generation facilities. While this approach does not add overall capacity, it shortens the distance for newer, stronger, and more stable power connections. Others are adopting a bring-your-own-power mentality, creating an opportunity for co-locatable power generation, such as fuel cells and nuclear power.
Bloom Energy Could Help AI Bypass the Power Bottleneck
Bloom Energy (NYSE: BE) has emerged as an AI-critical company because it can deliver power-generating units within months rather than years.
The shortened timeline is critical to monetizing the buildout and central to the stock’s price outlook.
Bloom Energy’s fundamental outlook has improved significantly. The company ended 2025 with approximately $20 billion in backlog, and management said that backlog continued to grow faster than revenue.
All the company needs to do is continue executing as it has been—which is to say, well.
Highlights from the fiscal Q2 release on July 28 included validation from the hyperscale community, signaling increased demand and confidence in Bloom’s ability to deliver at scale.
According to management, every major hyperscaler and more than a dozen neoclouds have approved the company.

Bloom’s Technology Advantage Extends Beyond Deployment Speed
Beyond speed, Bloom’s system offers advantages in co-locatable power quality, efficiency, environmental impact, and energy stability. The company’s solid oxide fuel cells generate electricity through an electrochemical process rather than combustion. When powered by natural gas or biogas, they still produce CO2 but generally have a lower carbon intensity and substantially fewer criteria pollutants than conventional fossil-fuel generation. When fueled by hydrogen, the systems can generate electricity without carbon emissions at the point of use.
Looking ahead, the company is also positioning its technology around direct-current (DC) power delivery as next-generation AI data centers move toward 800-volt DC architectures. Because conventional data centers typically receive alternating-current (AC) power that must be converted to DC for computing equipment, delivering power more directly could improve efficiency and reduce conversion losses.
Bloom estimates this could save billions of dollars on large-scale AI data-center projects by reducing electrical infrastructure, conversion losses, and equipment requirements, potentially strengthening its competitive position against traditional power solutions.
Brookfield Financing Expands Bloom’s AI Opportunity
Bloom’s long-term opportunity is also changing. No longer just a hardware seller, the company now offers power-purchase agreements, capacity leases, and other financing structures that allow customers to pay for power over time. That model is supported by Bloom’s partnership with Brookfield, which expanded its framework in June to as much as $25 billion to build and finance on-site power projects for AI infrastructure.
Under these financed arrangements, a third-party capital provider can purchase and own the Bloom Energy systems while the customer pays over time for power or capacity. Bloom makes money from the sales and can continue to earn service revenue over time, while the structure reduces the end customer’s upfront capital burden.
The net result is new, visible, and recurring service revenue alongside equipment sales.
Wall Street Is Raising Targets, But Bloom’s Rally Has Outrun Consensus
Analyst trends reflect the shift in Bloom Energy’s position and outlook.
MarketBeat currently tracks 26 analysts covering the stock, up from 19 a year earlier. The consensus rating remains Moderate Buy, with 13 Buys, 12 Holds, and one Sell.
Price targets are advancing aggressively, although Bloom’s September rally has pushed the stock ahead of Wall Street’s average expectations.
The $254.14 consensus target is up from $32.81 a year ago but sits nearly 8% below Bloom’s current share price.
At the high end, Mizuho’s $351 target, near Bloom’s existing all-time high of $351.28, implies roughly 27% upside.
September price action is bullish, with Bloom consolidating after a sharp rebound.
The MACD suggests the market is moving higher after hitting an extreme low and could continue rising in the coming weeks. The question is how the stock moves before topping out; a retest of the all-time high is likely. Further gains may depend on upcoming results, including those from hyperscalers indicating that the AI buildout will continue.
Scandium Supply Adds a Wild Card to Bloom’s Bull Case
One of Bloom’s biggest and more unusual risks involves supply-chain hurdles related to scandium oxide, a critical material used in its solid oxide fuel cells.
The company says there is no China connection and that adequate supply is available, but short-sellers disagree. In July, Hunterbrook alleged that Bloom was more dependent on China-linked scandium supply than it had disclosed. Bloom categorically rejected those claims in an SEC filing, saying it has sufficient scandium oxide to meet current demand and backlog and that its supply is not dependent on China.
The short-sellers allege potential wrongdoing in a class-action lawsuit, but conviction in those claims appears minimal. Short interest is up in September but remains relatively low, just below 7%.
For investors, the scandium issue is worth monitoring because any disruption to a critical input could affect Bloom’s ability to scale production, even as the company maintains that its supply is secure.
This email content is a paid sponsorship for The Oxford Club, a third-party advertiser of InsiderTrades.com and MarketBeat.
This ad is sent on behalf of The Oxford Club. 105 W Monument St, Baltimore, Maryland 21201. If you would like to optout from receiving offers from The Oxford Club please click here
If you need help with your account, don't hesitate to contact our U.S. based support team at [email protected].
If you no longer wish to receive email from InsiderTrades.com, you can unsubscribe.
© 2006-2026 MarketBeat Media, LLC. All rights protected.
345 N Reid Place, Sixth Floor, Sioux Falls, SD 57103-7078. United States of America..