 A Message From Brownstone Research Editor’s Note: Jeff Brown is the former tech executive who picked Nvidia in 2016 before it jumped 37,000% higher. He’s now recommending another AI stock that’s the same size Nvidia was 10 years ago. He calls it “Elon Musk’s One Stock Retirement Plan” because he believes Elon Musk is about to create massive demand for this company’s patented technology. Click here to see the details or read more below.
Dear Reader, I just found what I believe is the perfect tech stock… It checks all the boxes I look for in potential home runs… #1- It’s a leader in a tech breakthrough that could change the world… Its patented tech can produce intelligence up to 1,000 times FASTER than regular AI. #2- This AI breakthrough is protected by 150 patents… Meaning no other company can do what they do. #3- This stock is entering a phase of exponential growth… With Wall Street projecting sales to more than triple in the coming year. #4- It’s a relatively small company, unknown to most people… Which means there’s a ton of upside potential. In fact, this company is about the same size Nvidia was back in 2016… Before it exploded 37,800% higher... And while I can’t guarantee you’ll become a millionaire... That was enough to turn $5,000 into an entire retirement nest egg of $1,895,000. And last but not least… #5 It has a catalyst on November 11 that could send shares skyrocketing. Click here to see the details before it’s too late. We have so much to look forward to, Jeff Brown,
Founder & CEO, Brownstone Research P.S. I call this opportunity “Elon Musk’s One Stock Retirement Plan.” Why? Because Elon Musk just made two moves that I believe will create massive demand for this company’s patented technology. And I believe if you buy shares of this company BEFORE the upcoming announcement from its executive team… This single investment could potentially be your ticket to retirement.
Additional Reading from MarketBeat Navan's Strong Quarter Meets an AI Spending Reality CheckBy Chris Markoch. Published: 9/15/2026. 
Key Points- Navan shares fell over 15% after Q2 earnings despite 35% revenue growth, as investors worried rising AI spending could outpace future growth.
- The company also acquired BoomPop, an AI-powered event-planning platform, expanding its bundled travel, expense, and meetings offering without affecting guidance.
- Despite the sell-off, 17 analysts give NAVN a consensus Moderate Buy rating with a $30.50 price target, suggesting about 43% upside.
- Special Report: Here’s Why Trump Won’t End The Iran War
Navan Inc. (NASDAQ: NAVN) wouldn’t be the first company investors would think of as a target of the recent sell-off in artificial intelligence stocks. But that may be part of the trouble facing NAVN following the company’s Q2 earnings report for its 2027 fiscal year. In Navan’s case, a slowdown in AI growth would directly contradict the company’s current growth initiatives. The company is significantly increasing its AI spending, but investors are concerned that its growth may not keep pace. Navan (formerly TripActions) is a corporate travel and expense management platform that bundles business travel booking, corporate cards, expense reporting, and now meetings and events into one AI-powered system. It competes with fragmented, legacy point solutions in the market, including SAP Concur and American Express Global Business Travel (Amex GBT). Navan Delivered a Strong QuarterNAVN is down more than 15% since the earnings report, despite impressive headline numbers. Quarterly revenue rose 35% year over year (YOY) to $233 million. Perhaps more significantly, the company reported its third consecutive quarter of positive earnings on a non-GAAP basis. Both figures exceeded analysts’ expectations. The company also raised its full-year guidance for revenue, to 32% growth at the midpoint, and non-GAAP income, to a 9% margin. That would normally be enough to push the stock higher, but that wasn’t the case. The concern centers on the execution of its AI strategy. Navan reported that its AI support agent, Ava, handled roughly 60% of the company’s customer interactions in Q2. In addition, more than 50% of Ava’s calls ran on Navan’s own models, up from 30% in Q1. But at what cost? Navan reported a 46% increase in operating expenses, which management attributed to the company’s AI expansion. That creates the contradiction for investors: Navan is a growing company in a resilient sector, but that growth is being fueled by AI, creating an execution risk. That execution risk came into even sharper focus when the company announced an acquisition that adds another variable to the equation. Will BoomPop Change the Momentum?The same day Navan reported earnings, the company announced that it had acquired BoomPop, an AI-powered platform for planning corporate meetings and events. Terms were not disclosed. The deal wasn’t a surprise, which may explain the muted market reaction. Navan and BoomPop partnered earlier this year, and BoomPop’s technology was already integrated into Navan’s events offering before the acquisition made the relationship permanent. It’s a pattern the company has used before, most recently with its Smartrips deal in Latin America: partner first, prove out demand, then buy and fully integrate. BoomPop brings a track record that fits Navan’s consolidation pitch. The company says it has supported events for roughly 250,000 people at customers including Accenture (NYSE: ACN), Amazon (NASDAQ: AMZN), Alphabet (NASDAQ: GOOGL), Salesforce (NYSE: CRM), and Shopify (NASDAQ: SHOP). It estimates that it has reduced customers’ event-booking costs by about 30% on average. Management has pointed to meetings and events as a category in which most customer spending still occurs outside a managed platform. That’s the same space Navan has already targeted with travel and expense. For investors, the question is timing. Navan said the acquisition is expected to have no material impact on guidance, which helps rule out BoomPop as the source of the expense growth that spooked the market. But layering another integration onto a company already under scrutiny for rising costs explains why the post-earnings reaction ties into the AI spending debate. Will this be the kind of platform-building that pays off, or just another line item that investors have to trust management to convert into growth? How to Consider NAVN Post-Earnings?The gap down after the company’s earnings report has reversed nearly all the gains NAVN made over the summer. With negative sentiment surrounding AI, investors should watch the $18.30 area as potential support. At the same time, the relative strength index (RSI) has moved into oversold territory. While the RSI is not a perfect indicator, it can signal that bearish sentiment has become excessive. 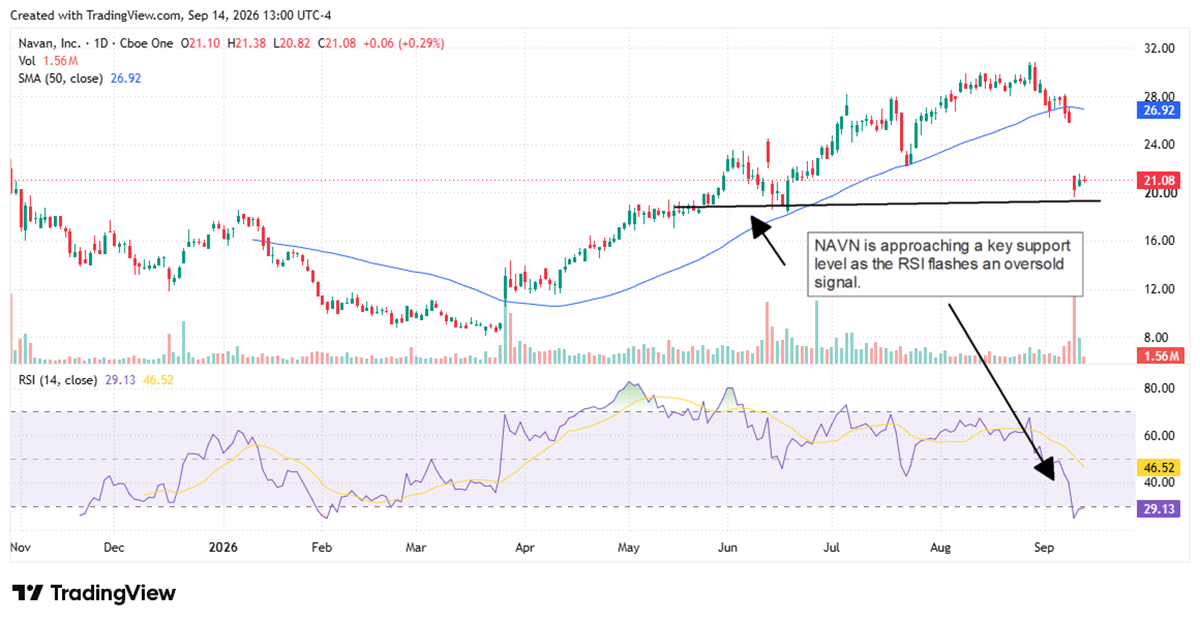
The Navan analyst forecasts on MarketBeat support a bullish outlook. Among the 17 analysts tracked by MarketBeat, NAVN has a consensus Moderate Buy rating and a $30.50 price target. That represents a gain of approximately 43% from recent prices. On the other hand, short interest in NAVN, while only around 10%, has remained higher than average over the last four quarters, which could keep some downward pressure on the stock. . | 