| China's government just launched a national initiative to deploy 10,000+ humanoid robots across manufacturing, logistics, and retail by end of 2026.
In Beijing, robots are already preparing coffee at convenience stores, packing orders at China Post warehouses, and running fully autonomous retail capsule shops — without a single human employee. | 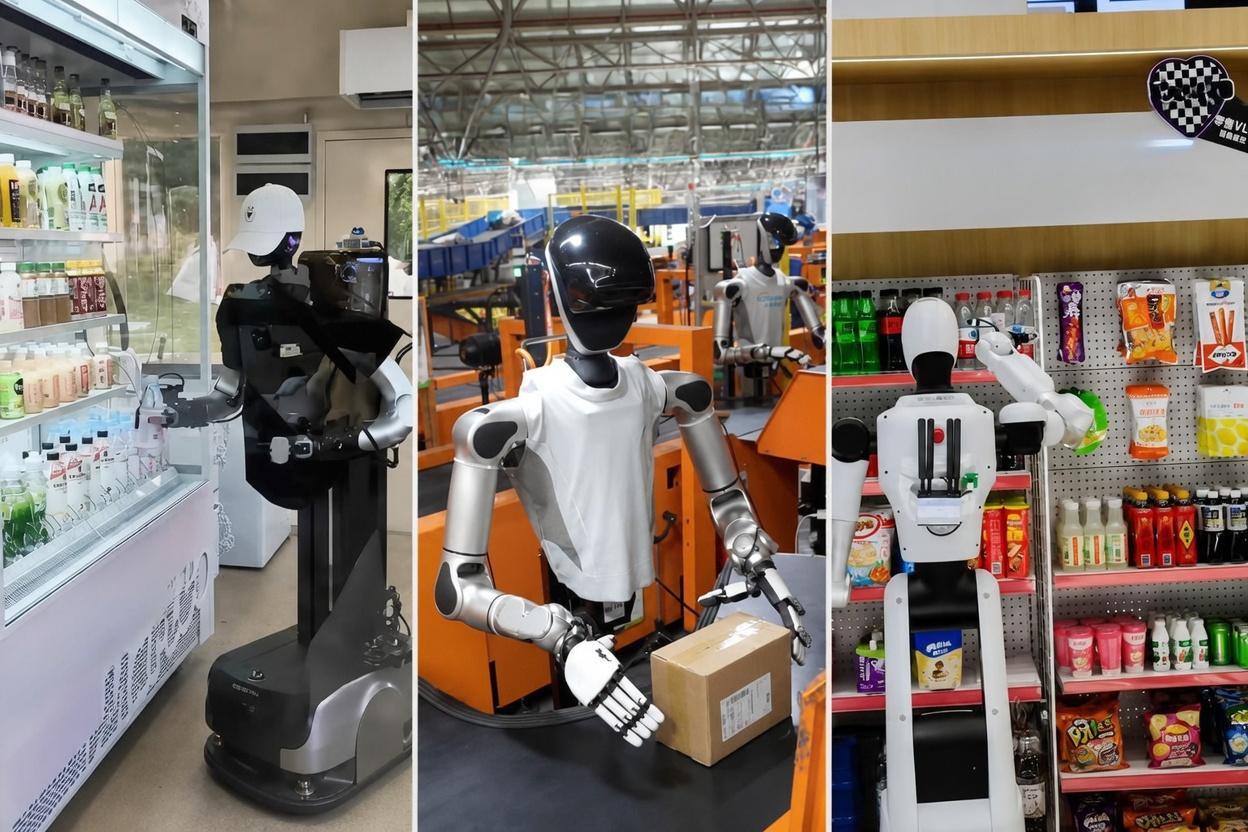 | Meanwhile, robotics companies globally have raised $55.8 billion so far this year — nearly double last year's record. America isn't sitting still either: Elon Musk is converting Tesla's Fremont factory from car production to robot production this summer. But here's the piece most investors are missing. Every single one of these robots — American, Chinese, or European — needs a vision system to function in the real world. And there's one company that supplies the best robotic "eyes" on the market, already embedded in Tesla's fleet. Jeff Brown — the man who called NVIDIA before it ran 23,000% — says this is the most important investment call of his career. See the Robotic Vision Supplier Nobody's Talking About | | | | If you would like to stop receiving these offers, please click here to unsubscribe. | |
|
|
Today's Market Update For You |
The Dust Settled Overnight. AI Stocks Are Leading the Rebound. Generac Jumped 20% on an Amazon Power Deal. The VIX Dropped 10%. The Market Decided the Fed Hike Was the Right Call.
|
Written by Harlan Talcott |
| The Morning After | - U.S. stocks opened strongly Thursday as the post-Fed selloff reversed. The S&P 500 rose +0.59% to 7,596. Technology (XLK), consumer discretionary (XLY), and materials (XLB) led. The Philadelphia Semiconductor Index (SOX) rose +3%, led by Intel (INTC), ARM, Marvell (MRVL), and Micron (MU). The Cboe Volatility Index (VIX) dropped 10% as options markets shed the pre-decision hedges that had inflated fear gauge readings through the week. A total of 18.4 billion shares traded Wednesday — well above the 20-session average of 15.3 billion — reflecting the post-decision positioning flush that set up Thursday's rebound.
- Generac Holdings (GNRC) surged more than 20% on a reported deal with Amazon for power infrastructure — the clearest single-stock signal of Thursday's session that the AI power buildout story remains intact and well-bid regardless of the rate environment. NBIS shares jumped on price increases. Crown Holdings (CRWV) fell on bond and stock offering headlines. Financials (XLF) and energy (XLE) lagged — the rate-sensitive and oil-exposed sectors absorbing the Fed decision's direct impact while the AI infrastructure trade bid higher.
- Weekly jobless claims came in better than expected — reinforcing the labor market picture that gave the Fed cover to hike without invoking recession risk. The Philadelphia Fed manufacturing survey was down from prior month but above consensus. Housing data showed weakness as mortgage rates rise — the most direct consumer-facing consequence of Wednesday's rate decision. The Bank of England held at 3.75% in a 6-3 vote Thursday morning. The Bank of Japan rate decision is expected overnight, with a 25 basis point hike widely anticipated.
| | | The dust settled in roughly 16 hours. U.S. stock futures were rebounding before Thursday's open, Treasury yields were easing, oil was falling on the Saudi-Oman workaround, and Motley Fool's midday wrap described a combination of factors helping to overcome the initial post-Fed reaction: falling oil prices, lower Treasury yields, and "increased confidence that the Fed is committed to curbing inflation." That last factor is the one worth sitting with. Warsh's hawkish press conference — which sent the S&P down 1% and 2-year yields to their highest since 2024 on Wednesday afternoon — is being read the morning after not as a threat to growth but as evidence of institutional credibility. Markets decided overnight that a Fed that is serious about inflation is a better outcome than a Fed that is not. | | Generac +20% and the Amazon Power Deal — Why the AI Infrastructure Trade Didn't Blink | | Generac Holdings surging more than 20% on a deal with Amazon for power infrastructure is Thursday's most specific data point about where institutional capital moved after the Fed decision. Generac manufactures backup power systems — generators, energy storage, grid services technology — that have become critical infrastructure for data centers running AI workloads at near-100% GPU utilization. Amazon's deal is a direct investment in the physical power layer that AI compute requires. At $6.06 per gallon diesel and climbing electricity costs, the economics of data center power security have moved. The AI buildout's power problem — not enough reliable grid capacity where the data centers are going — is the market that Generac is selling into. The 20% single-session move is a rerating, not a trade. | | The semiconductor sector's 3% gain on the SOX — Intel, ARM, Marvell, Micron all up — reflects the same thesis running through a different supply chain. The July FOMC minutes explicitly flagged AI buildout costs — chips and steel for data centers, smartphones, computer equipment, power — as contributing to elevated core goods inflation. The committee hiked Wednesday in part because that AI-driven inflation channel is broadening. The same session that produced the 1% S&P decline also produced a narrow subset of AI infrastructure names — semiconductors, power equipment, cloud — that held or gained. Thursday's rebound extended that divergence: the AI trade did not treat Wednesday's hawkish hike as a negative for the capital-spending cycle. It treated it as confirmation that the macro environment is serious enough that the infrastructure underlying it is not optional. | | 📊 Thursday Morning Sector Scorecard | Leading ↑ | Technology (XLK), Consumer Discretionary (XLY), Materials (XLB) · SOX +3% (INTC, ARM, MRVL, MU) · GNRC +20% on Amazon power deal · NBIS up on price increases | | Lagging ↓ | Financials (XLF), Energy (XLE) · CRWV down on bond/stock offering · Housing data weak on rising mortgage rates | | Fear gauge | VIX -10% — pre-decision hedges unwound · options expiration tomorrow adds to positioning flush | | Data Thursday | Jobless claims: better than expected · Philly Fed: down from prior, above consensus · Housing: weak | | | | | |
Legendary investor James Altucher just dropped a MAJOR new bombshell about Elon Musk.
It’s a project James says will be even BIGGER than SpaceX – creating up to 1.8 million new millionaires over the coming years – starting on Sept. 25th. And the pieces behind all of it are sitting inside this case – which he reveals 100% FREE in this brief video. |
| Housing Data Showed Weakness — the First Direct Consequence of 7% Mortgages | | Thursday's housing data — described in Investrade's mid-morning look as showing "weakness as mortgage rates rise" — is the first scheduled data point that captures the effect of the rate environment that was in place before Wednesday's hike. The 30-year conforming mortgage rate was at 6.97% and jumbo rates at 7.03% heading into the Fed decision. Both will move higher in the days following the hike to a new fed funds range of 3.75–4.00%. Housing permits, starts, and existing home sales have been softening for several months as the current rate environment has steadily reduced the pool of buyers who can qualify under standard debt-to-income underwriting at current home prices. The data Thursday is consistent with that trend continuing. It does not constitute a housing market collapse; it constitutes a housing market that is adjusting to a rate environment that has made the monthly payment calculation harder for the marginal buyer. | | The specific housing data point that moves Thursday's analysis is not the level but the direction. The Fed's rate decision Wednesday adds roughly 25 basis points to the mortgage rate trajectory, and markets are pricing an additional 75–100 basis points of Fed hikes over the next year. If the full implied path to 4.6% materializes, the 30-year conforming mortgage would approach 7.5–7.75%. At that level, the existing home sale market — which has remained constrained by the lock-in effect of homeowners holding 2–3% mortgages unwilling to sell and take on a new 7%+ loan — compresses further, new construction slows as buyer financing becomes more restrictive, and the housing market's contribution to GDP begins to show up in the data in ways that the current Thursday snapshot does not yet capture. | | What Thursday's Rebound Is Pricing — and What It Is Not | | Thursday's S&P +0.59% rebound from Wednesday's -0.5% post-decision close is not a market that has processed the full implications of a hawkish Warsh with a dot plot showing 16 of 18 members expecting more hikes. It is a market that has priced the immediate relief factors: falling oil on the Saudi-Oman workaround, lower Treasury yields as the post-hike repricing stabilizes, pre-decision hedges unwinding into options expiration Friday, and the AI infrastructure trade reasserting on Generac and semis. Those factors can all be true simultaneously with a rate path to 4.6% and housing data showing weakness. They do not cancel the tighter financial conditions the Wednesday decision introduced. They represent the short-term positioning adjustment that always follows a fully-priced decision — the options market clearing, the hedges coming off, the fear gauge retreating from its pre-announcement peak. | | The Motley Fool characterization of Thursday's drivers — "increased confidence that the Fed is committed to curbing inflation" — is the right read of the market's message. A Fed that delivers a hawkish hike unanimously, revises the neutral rate upward, removes the 2027 cut, and has a chair who says "not one and done" has re-established a credibility position that the market was not certain about before Wednesday. That credibility trade — buying equities because a credible central bank reduces the long-run inflation risk premium — is a real phenomenon in monetary policy history. It is also a trade that can reverse on the next data point that suggests the credibility commitment is being tested. The next test is October's CPI, which will capture September's oil prices at the post-pipeline-shutdown level. That data releases mid-October, two weeks before the next FOMC meeting, into a housing market already showing weakness and a mortgage rate already at 7%. | | | | Sources: Investrade · Yahoo Finance · Motley Fool · BabyPips · CNBC | |
|
|
| If we go quiet — look in promotions, updates, or wherever your inbox files things it hasn't figured out yet.
[email protected] is on The Risk Tolerance list because you opted in before the crowd caught on.
Unsubscribe. We'll part ways cleanly.
If something's off, you can reach us here
Privacy Policy
|
|
|
|