Hello,
Welcome to our flagship newsletter, MarketBeat Daily Ratings.
We'll deliver the latest "Buy" and "Sell" ratings from Wall Street's top-rated analysts directly to your inbox each morning.
But first, we need you to do two quick things:
1. Hit reply, and send a simple "Yes." Just one word. This tells Google (and other emails providers) that you actually want to get our newsletter.
2. After that, this link to confirm your subscription. That will tell us that you received our welcome email and that we should start sending your daily report.
Confirm your subscription here.
After you have completed these two steps, we would like to gift you a free copy of one of our most popular investing reports: 7 Stocks to Buy and Hold Forever. You can download the report with this link.
Thank you again for subscribing. We look forward to being an important part of your investing journey
Matthew Paulson
Founder and CEO, MarketBeat.
P.S. If you didn’t intend to subscribe, no problem—you can unsubscribe with this link.
(ARReply-161)
Exclusive Article from MarketBeat.com Copper’s Record Rally Highlights a Deeper Supply ProblemBy Jeffrey Neal Johnson. Date Posted: 9/13/2026. 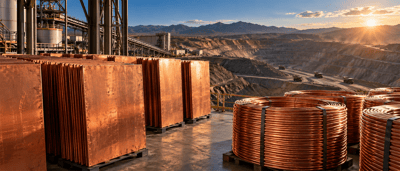
Key Points- Copper prices recently reached record highs as tightening mine supply, AI infrastructure, and grid investment support long-term demand.
- Freeport-McMoRan and Southern Copper provide direct exposure to higher copper prices through large-scale, established mining operations.
- Near-term tariff uncertainty and weaker Chinese imports could create volatility even as longer-term copper supply constraints remain in place.
- Special Report: The company SpaceX cannot operate without
Copper prices recently reached historic milestones, with COMEX futures crossing approximately $6.87 per pound and London Metal Exchange (LME) cash contracts testing roughly $14,779 per metric ton. A headline-driven pullback tied to delays in proposed U.S. refined copper tariffs briefly interrupted that advance. For investors analyzing the physical economy, separating short-term trade-policy noise from multi-year structural shortages is essential.
Beneath day-to-day market sentiment, the physical fundamentals supporting copper remain resolute. From artificial intelligence (AI) data centers to utility-scale power-grid upgrades, demand is accelerating as global mine production enters its first annual decline in nine years. Understanding how these physical deficits interact with producer balance sheets helps explain why the red metal sits at the center of the global energy transition.
Shock Value: Testing the $15,000 Resistance Level
Trump has called an Iran deal close 38 times since the war began, yet the fighting keeps flaring back up.
One day it's a ceasefire, the next it's bombs again. The back and forth may be masking a bigger story most investors are missing.
See the real reason this conflict may never fully end. Uncover the real reason Trump may never end this war Global copper benchmarks spent early September 2026 pressing toward the unprecedented $15,000-per-metric-ton threshold. On the COMEX exchange, active contracts touched a record near $6.87 per pound, equivalent to approximately $15,140 per metric ton, before settling around $6.85 per pound. Across the Atlantic, LME three-month contracts climbed to about $14,779 per ton before steadying near $14,694 per ton.
That upward momentum paused after reports indicated that a White House proposal to impose refined copper tariffs had stalled because of concerns about domestic manufacturing costs. The headline prompted an extended-hours sell-off in major mining equities, unwinding speculative tariff-related price premiums.
Investors recognize that import tariffs served merely as a short-term catalyst, not the foundation of the rally. Trade policy can redirect regional shipping routes, but it cannot manufacture copper ore out of thin air. The real pricing pressure stems from a widening physical deficit between extraction volumes and non-discretionary industrial demand.
Circuit Breakers: Infrastructure Clashes With Fixed Supply
The modern industrial economy relies on refined copper because it remains the standard commercial conductor for electrical transmission. Two structural drivers are pushing consumption beyond historical trends.
High-density artificial intelligence data centers operated by leading technology corporations require unprecedented power delivery. Distributing megawatts of electricity to server racks requires dedicated step-down transformers, switchgear and thick copper busbars. Because of thermal constraints and electrical-conductivity requirements, engineering teams cannot easily substitute aluminum without compromising energy efficiency.
Utility-scale electrical grids are undergoing comprehensive modernization to connect renewable generation assets. Wind and solar installations require four to six times as much copper per megawatt of capacity as legacy thermal power plants.
Long-term models from the International Energy Agency indicate that annual copper demand could reach approximately 42 million metric tons by 2040. Industry analysts estimate that this pace could generate a persistent annual supply gap of roughly 12 million metric tons, representing a 24% deficit. When demand is non-discretionary, pricing power sits squarely with low-cost extractors.
Short Circuit: Smelting Bottlenecks Choke Refined Supply
While long-term demand accelerates, upstream extraction is contracting. Global copper mine output declined about 1.1% in the first half of 2026, while concentrate production dropped approximately 2.6%. This performance puts the mining sector on track for its first full-year mine-supply decline since 2017. Operational challenges across Chile, Indonesia and the Democratic Republic of the Congo have curtailed output from several Tier 1 facilities.
This raw-material shortage is placing severe operational pressure on intermediate processors. Spot treatment and refining charges, known across the industry as TC/RC, have fallen into negative territory. When TC/RC rates turn negative, smelters lose money on every ton of concentrate processed. Consequently, metallurgical facilities throughout Asia are scheduling unannounced maintenance shutdowns and reducing furnace run rates.
These processing bottlenecks restrict refined cathode availability. While stockpiles in U.S. COMEX warehouses grew because of commercial inventory positioning ahead of potential tariffs, combined inventories on the LME and Shanghai Futures Exchange have dropped below 300,000 metric tons. That volume represents less than half of COMEX holdings, leaving global manufacturers exposed to localized delivery squeezes.
Amping Up Profits: Operational Leverage Powers Extraction
For equity investors, structural deficits translate directly into operational leverage. Operational leverage occurs when a revenue increase leads to a disproportionate gain in operating income. Because mine-development and heavy-machinery costs are largely fixed once a deposit is operational, rising realized metal prices flow directly to cash flow.
Sector models show that for every sustained 10-cent increase in the copper price per pound, major unhedged producers generate between $425 million and $450 million in incremental annual earnings before interest, taxes, depreciation and amortization (EBITDA).
Freeport-McMoRan (NYSE: FCX) illustrates how this leverage operates. Freeport-McMoRan posted second-quarter earnings of 74 cents per share, surpassing the consensus estimate of 62 cents.
With a conservative debt-to-equity ratio of 0.25 and annual operating cash flow of about $4.09 per share, Freeport-McMoRan maintains a forward price-to-earnings-growth (PEG) ratio of 0.75, alongside projected earnings growth of approximately 34%.
Southern Copper Corporation (NYSE: SCCO) demonstrates how low cash costs support bottom-line performance.
Southern Copper Corporation generated a pretax profit margin of 55.78% and a return on equity of 49.04% over the trailing 12 months, supporting a dividend yield of around 2.10%.
Unlike during past commodity expansions, corporate leadership is avoiding speculative greenfield projects.
Permitting delays and declining ore grades mean that building a new open-pit copper mine now takes 15 to 20 years from discovery.
As a result, producers are directing capital toward balance-sheet liquidity and dividend distributions, keeping new physical supply off the market.
Grounding the Portfolio: Finding Value in Policy Pullbacks
Investors should balance long-term tailwinds against near-term friction. When spot prices trade near historic highs, industrial consumers occasionally pause orders. In China, copper imports fell to roughly 382,000 metric tons in August 2026, marking a six-year low for the month as domestic fabricators resisted elevated spot prices. Ongoing adjustments to international trade policy may also create brief periods of price volatility.
Wall Street forecasts reflect these conflicting forces. Consensus coverage on Southern Copper Corporation is Reduce, with an average price target of $146.84, well below the current share price. The stock also trades at an elevated price-to-sales ratio of roughly 12 times, reflecting a premium valuation after its strong run. Meanwhile, Freeport-McMoRan has a Moderate Buy consensus among 25 analysts, with an average price target of about $69.75 and an upper target of $85.
Pragmatic investors can view headline-driven price dips as an opportunity to assess physical commodity exposure. Rather than reacting to daily policy updates, fundamental allocators often favor low-cost, unhedged producers positioned to benefit from multi-year grid modernization. Tracking quarterly corporate earnings reports and warehouse-inventory metrics can help market participants identify when physical demand resumes its upward trend. |