Hello,
Welcome to our flagship newsletter, MarketBeat Daily Ratings.
We'll deliver the latest "Buy" and "Sell" ratings from Wall Street's top-rated analysts directly to your inbox each morning.
But first, we need you to do two quick things:
1. Hit reply, and send a simple "Yes." Just one word. This tells Google (and other emails providers) that you actually want to get our newsletter.
2. After that, this link to confirm your subscription. That will tell us that you received our welcome email and that we should start sending your daily report.
Confirm your subscription here.
After you have completed these two steps, we would like to gift you a free copy of one of our most popular investing reports: 7 Stocks to Buy and Hold Forever. You can download the report with this link.
Thank you again for subscribing. We look forward to being an important part of your investing journey
Matthew Paulson
Founder and CEO, MarketBeat.
P.S. If you didn’t intend to subscribe, no problem—you can unsubscribe with this link.
(ARReply-161)
Just For You Copper Surges as Shifting Trade Policy and AI Demand CollideAuthored by Chris Markoch. Posted: 9/2/2026. 
Key Points- Copper prices hit record highs above $6.72 per pound, driven by Section 232 tariffs on copper products and surging AI-related data center demand.
- Freeport-McMoRan, Southern Copper, and BHP have all posted strong share price gains and earnings growth as direct or diversified plays on the copper rally.
- Some analysts warn that a portion of copper's price surge reflects a temporary tariff-driven policy premium that could fade once trade rules are finalized.
- Special Report: SpaceX is offering you shares. Don't take them.
Investors looking to capitalize on the artificial intelligence infrastructure boom have increasingly turned to basic materials, and industrial metals—copper chief among them—are having a moment few saw coming even a year ago. What started as a trade-policy story has merged with a structural demand story, and the combination is rewriting price records almost weekly.
Copper Prices Rise on Tariffs and AI Infrastructure Demand
Comex copper touched a fresh all-time high above $6.72 per pound in late August and has continued to trade near those levels into September. Two forces are doing the heavy lifting.
A small Colorado company has secured rights to technology that could prevent the U.S. public power grid from collapsing — and billionaire Sam Altman is now an investor.
This under-the-radar firm is drawing serious attention from those watching the energy infrastructure space closely. Click here to learn this company's name for free today First, there's the current tariff policy. Washington imposed a 50% Section 232 tariff on semi-finished copper products and copper-intensive derivatives in 2025, later expanding the rate structure in April 2026 while leaving refined cathode largely exempt—for now.
That exemption has been enough to trigger a scramble. Traders have spent months rerouting metal into U.S. warehouses ahead of the possibility that refined copper will eventually be swept into the tariff policy, and Comex inventories have ballooned to levels that would have seemed unthinkable two years ago.
The catch is that once copper lands in a bonded U.S. warehouse, it's largely stuck there. So what was supposed to be a comfortable global surplus has effectively been drained from the rest of the world. Analysts at CRU, who had projected a healthy 2026 surplus, now describe the non-U.S. market as balanced at best, with some warning that it could look like an outright deficit if these flows continue.
Second, and less reversible, is demand. Data centers have become a source of copper demand that doesn't flex with price the way industrial buying typically does. Hyperscalers need the wiring, bus bars and cooling infrastructure regardless of what copper costs per pound.
That's a new kind of buyer for a market that used to take its cues almost entirely from construction and manufacturing cycles. Layer on grid modernization and electrification, and you have a demand base that's structurally higher even before tariff-driven stockpiling is factored in.
Freeport-McMoRan Offers Direct Exposure to Rising Copper Prices
Freeport-McMoRan (NYSE: FCX) is the most direct U.S.-listed proxy for copper prices and the largest domestic producer of refined copper. That means it stands to benefit most if the exemption narrows.
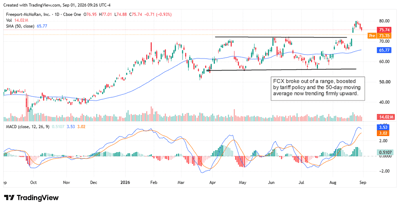
The FCX chart confirms that story. Shares have risen from the low $40s a year ago to the mid-$70s, with the 50-day moving average now trending firmly upward and MACD back in bullish territory after a rocky spring.
Q2 2026 net income attributable to common stock came in at $984 million, or 68 cents per share. That pushed first-half net income up 65% year over year, even as headline revenue slipped to $7.03 billion from $7.58 billion a year earlier. The decline was driven by lower Indonesian gold and copper volumes during the phased Grasberg Block Cave ramp-up, not by weaker pricing.
Realized copper prices averaged $6.17 per pound in the quarter, and U.S. mining operations more than doubled their operating income contribution compared with the first half of 2025. That underscores how much of FCX's earnings power is now coming from the domestic side of the business, which the tariff regime is designed to protect.
Southern Copper Combines Low Costs With Copper Price Leverage
Southern Copper (NYSE: SCCO) is the low-cost operator of the group, and its Q2 2026 numbers underline why. Revenue rose roughly 41% year over year to $4.29 billion, while net income jumped more than 70% to $1.67 billion.
Byproduct credits from silver, molybdenum and zinc have been the real story. They pushed operating cash cost per pound of copper down to just a nickel, from 63 cents a year earlier. That's a cost structure in which margin expansion accelerates disproportionately as copper prices climb, since so little of the cost base remains exposed once byproducts are netted out.
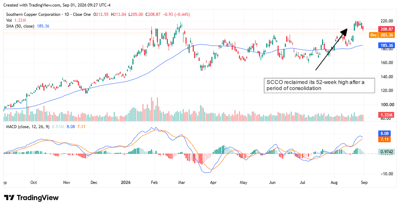
The chart shows that investors understand the benefits of the company's operating leverage. SCCO has more than doubled from its spring lows and set a fresh record above $220 in late August before pulling back slightly.
BHP Gives Investors Diversified Exposure to the Copper Boom
BHP Group (NYSE: BHP) is the diversified pick, and for readers who are less risk-tolerant, it's arguably the easiest entry point into the copper thesis.
For the first time in the company's history, copper generated more than half of BHP's underlying EBITDA in fiscal 2026—about 54%, or roughly $18 billion—overtaking iron ore as the group's largest earnings contributor.
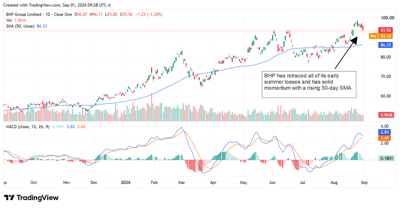
Underlying attributable profit rose 30% to $13.2 billion for the year. BHP's chart shows the same steady uptrend as its pure-play peers, climbing from the high $50s a year ago to near $96, though it has pulled back modestly from its late-August peak alongside the rest of the group. The tradeoff for investors is that while BHP is less tethered specifically to copper, it also has lower concentration risk than the other names on this list.
Copper’s Rally Faces a Risk From Tariffs and Policy Uncertainty
Not everyone treats $6.70 copper as a clean read on global growth. Some analysts note that the price carries a real "policy premium" tied to tariff uncertainty and the rush to beat any rule change, rather than reflecting pure consumption strength.
Glencore's CEO has even argued that a final tariff decision, whichever way it goes, could take some heat out of prices simply by ending the uncertainty. The fundamentals—AI-driven demand, mine-supply constraints and grid buildout—are real and durable, but part of today's price also reflects a timing trade that could unwind once the tariff picture becomes clearer. |