 A Message From Weiss Ratings Dear Reader, In 1929, a 20-something Wall Street rookie named Irving Weiss noticed something nobody else did. 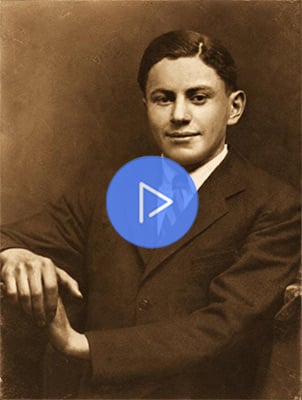
While brokers partied and shoeshine boys handed out stock tips, Irving buried himself in financial reports at the New York Public Library. What he found told him America was about to face one of the biggest financial disasters in history. He warned everyone. The veteran brokers laughed at him. Then came Black Monday. The Dow crashed nearly 13% — followed by another 12% the very next day. The investors who listened to Irving avoided the wipeout. He didn’t just sound the alarm. He also knew what would work. In fact, he was able to take $500 and turn it into what would be worth $2 million today. That strange secret Irving discovered became the foundation of what we know today as Weiss Ratings — the system a study published in The Wall Street Journal ranked #1 for investment performance. And right now, it's flashing its most urgent warning in years. A radical shift could hit the market in the back half of 2026 — sending some of today's most popular stocks crashing, while a handful of little-known names could soar. Now we're opening up full access to Weiss Ratings Plus — including the names of the stocks to avoid and the ones we believe are set to surge. Learn how to gain access by clicking here now. Regards, Tom Mustin
Host, Weiss Ratings P.S. Weiss Ratings accurately called the Dot-Com Bust, the 2008 crisis, and the brief 2020 crash. Now it's calling something entirely new. Click here to learn more.
This Month's Bonus News Is Abercrombie & Fitch's Hot Streak Just Getting Started?Written by Sam Quirke. Originally Published: 9/1/2026. 
Key Points- Abercrombie & Fitch shares have more than doubled since late May after strong quarterly results and raised guidance boosted investor confidence in the retailer.
- Argus upgraded the stock to Buy with a $162 price target, while Citi downgraded it to Neutral, citing valuation and risk/reward concerns after the rally.
- A one-time tariff refund flattered recent profits, and the stock's rising valuation multiple leaves less room for error in future earnings reports.
- Special Report: Get this “Fed ticker” before September 16
Few stocks, let alone retail names, have enjoyed a run quite like Abercrombie & Fitch Co. (NYSE: ANF) over the past few months. Since late May, shares have more than doubled, climbing to their highest level since January 2025 and nearly erasing the brutal 60% sell-off that weighed on the stock last year. It has been an impressive recovery, and the momentum shows little sign of fading. The latest fuel came from two sources in quick succession: a record quarterly report last week, followed by a fresh analyst upgrade this week that suggests the good times are far from over. Together, they offer the clearest signal yet that this lifestyle retailer may have further to climb. The question for investors, then, is not whether Abercrombie has turned a corner—it plainly has—but whether the shares can maintain their blistering pace. After a rally of this magnitude, is the hot streak only getting started, or has the easy money already been made? A Standout QuarterLast week's report left little doubt about the strength of the business. In addition to delivering a solid beat on the headline numbers, Abercrombie reported sales growth across the board, while management was confident enough to raise its guidance for the rest of the year. What stood out was the 8% year-over-year growth at the company's namesake Abercrombie brand, which helped re-establish momentum that had recently slowed. Meanwhile, the company's younger-skewing Hollister brand made solid progress in acquiring new customers, helped by a deal with Target Corporation (NYSE: TGT) that puts its clothes in more than 1,500 Target stores. Management also announced a fresh share repurchase program, one of the clearest signals it can send that it believes its own shares are undervalued. Overall, it was a strong report, so the subsequent 35% jump in the stock was not entirely surprising. An Upgrade That Fanned the FlamesA major vote of confidence from Wall Street quickly followed the strong quarter. On Monday, Argus lifted its rating on the stock to Buy, arguing that the upside momentum at both brands has room to run. It also set a new $162 price target for Abercrombie shares, implying potential upside of roughly 13% from recent prices. Christine Dooley, the Argus analyst behind the call, made a clear case for why the momentum can continue. In her view, the company's sales have decisively turned after management worked to put both brands on a more sustainable footing. Hollister was already performing well, she noted, and now the flagship Abercrombie brand has staged a revival of its own, giving the retailer two engines of growth rather than one. What the Doubters Are SayingHowever, not everyone is convinced that the good times will continue. After the stock jumped following last week's results, Citi took the opposite approach and turned cautious, downgrading Abercrombie from Buy to Neutral. Analyst Paul Lejuez acknowledged that there was plenty to like in the report, but said that after such a sharp move, the stock's risk-reward profile was no longer attractive. There was also a catch buried in the headline numbers: A substantial portion of the quarter's profit came from a one-off tariff refund, a windfall that flattered the results and will not recur indefinitely. Stripping out that temporary boost, the business is still performing well, but its underlying profitability is more modest than the reported figures suggest—something investors chasing the stock should remember. Abercrombie's valuation is also starting to look less like a bargain. This time last year, the stock traded at 7x earnings; today, that multiple is above 12. Such a re-rating leaves far less margin for error in future results and puts additional pressure on the company to keep delivering. Plenty of Momentum, But Beware Some Profit-TakingSo where does that leave investors today? The bull case remains compelling: Abercrombie is undoubtedly a well-run business with real momentum behind it. Against that are two main bearish caveats—the flattering effect of a $100 million one-off tariff refund and a share price that has already come an awfully long way in a short period. For now, shares appear to be consolidating near the upper end of last week's jump, around the $150 mark, and it would be no surprise to see some profit-taking in the coming sessions. That might actually be the best-case scenario for investors on the sidelines, as it would cool the recent run and give them a chance to buy into a stock that clearly has significant momentum behind it.
11780 US Highway 1,
Palm Beach Gardens, FL 33408-3080
Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved.
11780 US Highway 1,
Palm Beach Gardens, FL 33408-3080
Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved. | 
