 A Message From Banyan Hill Publishing Dear Reader, I hesitated to even send you this. After what I heard… After who told me… On January 7th… just outside Washington, D.C… I sat across from a man whose family has been tied to global power for decades. Oil deals. Intelligence circles. Government insiders. He leaned in and told me something that changed everything I thought I knew about the Iran war. What you’re seeing on the news? It’s not the real story. Not even close. The strikes… the chaos… the escalation… It’s all part of something much bigger. A global deal worth trillions. And the only reason I know this is because of him — an anonymous contact who risked everything to pass this information along. I verified it. Cross-checked it. Dug deeper. And what I uncovered is something every American investor needs to see immediately. Click here to see the full breakdown before it’s too late. It’s a coordinated move that could reshape the global economy for decades. But you need to see it for yourself. Go here now and uncover the real reason behind the Iran war. Regards, 
Addison Wiggin Founder, Grey Swan Investment Fraternity
Further Reading from MarketBeat 3 ETFs That Could Move as Rate Expectations ShiftAuthored by Dan Schmidt. Article Posted: 9/6/2026. 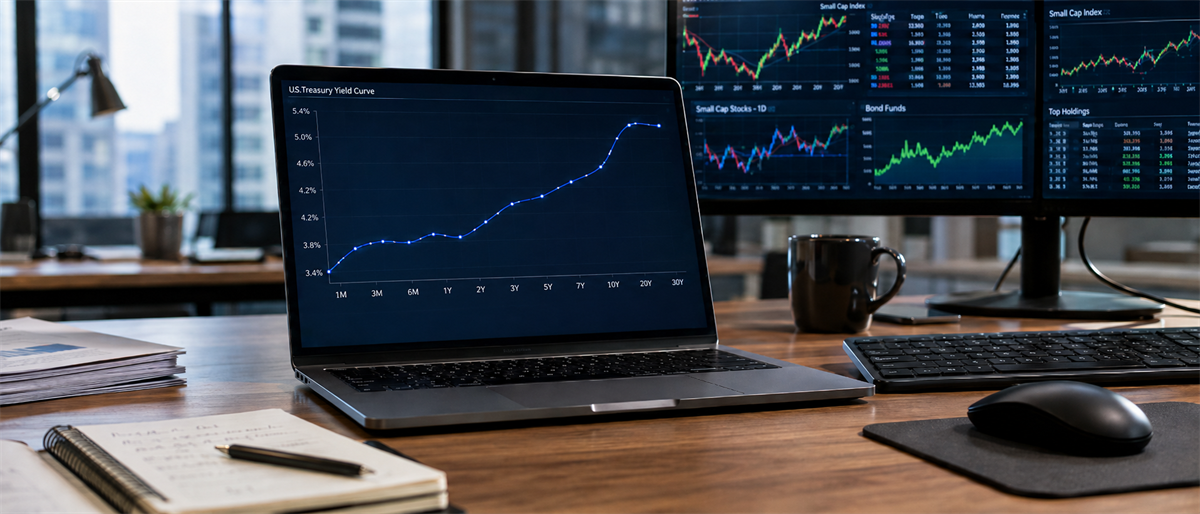
Key Points- August nonfarm payrolls rose 162,000, far exceeding forecasts, pushing the 2-year Treasury yield to its highest level since January 2025.
- Stronger jobs data raised the odds of a September Fed rate hike above 60%, shifting focus toward the upcoming August CPI report on Sept. 11.
- Investors can position for hawkish or dovish Fed outcomes through IWM, XLF, and TLT, which respond differently to changing interest rate expectations.
- Special Report: The 38% Crash Warning Every Retirement Saver Needs to Read Right Now
The interest-rate whipsaw intensified as August nonfarm payrolls grew by 162,000, well above the consensus estimate of 53,000. The S&P 500 flipped from green to red on the news, and the 2-year Treasury yield rose to 4.416%, its highest reading since January 2025. Once again, the Federal Reserve’s interest-rate decision was thrown a curveball, and the committee must now decide whether to hike rates or remain on hold until December. That decision has different implications for various parts of the economy, and investors can bet on their assumptions through highly liquid exchange-traded funds (ETFs). What Shifting Expectations Mean for This CycleTo hike or not to hike—that is the question. Despite political pressure for easier policy, a cut is not the market’s base case. More jobs are obviously better than fewer jobs, but this is another data point pointing to stickier inflation, and the market has repositioned itself to reflect that reality. The CME FedWatch tool showed odds of a September rate hike jumping above 60% in the hours after the jobs data was released. A warming labor market recalibrates the Fed’s decision-making process with roughly two weeks to go until the critical September Federal Open Market Committee (FOMC) meeting. July PCE inflation was still uncomfortably high at 3.7%, and three FOMC members dissented in favor of a hike at the July meeting. A strong labor market report puts the dual mandate’s focus squarely back on inflation, which remains supply-driven. The August jobs report simply shifted the market’s focus to the August Consumer Price Index (CPI) release on the morning of Sept. 11. 3 ETFs for a Changing Rate EnvironmentThe September rate decision remains murky, and the CPI report may do little to clarify matters. But long-term rates continue to move upward, and the average 30-year mortgage rate is approaching its 2025 high. A hawkish or dovish Fed would affect the economy in different ways, and these three ETFs provide options for playing the various outcomes. Russell 2000: Where Rate Signals CollideThe iShares Russell 2000 ETF (NYSEARCA: IWM) is one of the most cost-effective ways to gain exposure to the vast ecosystem of small- and mid-cap stocks on U.S. exchanges. It charges a small 0.19% expense ratio and has amassed more than $80 billion in assets under management (AUM). Over 90% of the fund’s holdings are U.S.-based, and no stock makes up more than 0.38% of the total portfolio. The Russell 2000 Index is an interesting study in rate signals. The index is heavily weighted toward domestic companies, so strong U.S. job growth generally leads to positive earnings growth for these stocks. But these companies are also the most sensitive to high rates because their debt is typically floating-rate or closer to maturity than large-cap debt. A trend shift in IWM will likely offer clues about which factor is carrying more weight in the small-cap environment. The Financial Sector: Getting the Best of Both WorldsRates and job growth do not present a double-edged sword for the financial sector. When rates rise, banks get better yields on their bond holdings and higher net interest margins on the loans they offer. And when employment strengthens, consumers have greater access to credit, allowing banks to take on higher-quality loans. A high-rate environment with a strong labor market is a Goldilocks scenario for banks, which is why so many stocks in this space have hit new all-time highs this year. The Financial Select Sector SPDR ETF (NYSEARCA: XLF) is the cheapest way to access the financial sector, with a 0.08% expense ratio and more than $55 billion in AUM. The fund’s top 25 holdings account for more than 77% of its portfolio. The largest holdings include large-cap financial firms such as JPMorgan Chase & Co. (NYSE: JPM), Berkshire Hathaway Inc. (NYSE: BRK.B), and Visa Inc. (NYSE: V). Long-Dated Bonds: Duration Risk No Longer Provides a HedgeOur final ETF is the iShares 20+ Year Treasury Bond ETF (NASDAQ: TLT), which has a 0.15% expense ratio and an average duration of 16 to 17 years in its nearly $47 billion bond portfolio. A hawkish Fed may not directly affect a fund with maturities this far out, but TLT’s role as an equity hedge may not last if the drawdown is inflation-driven rather than growth-driven. Strong job growth argues against easing, and higher rates on long-dated bonds mean the prices of existing bonds fall. Since Treasuries are sold at fixed rates, older issues must sell at lower prices to compete with newer bonds offering higher coupon rates. TLT sells its bonds once they reach less than 20 years to maturity and replaces them with newer, longer-dated bonds. In a high-rate environment, TLT must sell its older bonds and replace them with newer bonds carrying higher yields, creating a mismatch that lowers the value of its holdings. One important caveat: TLT’s price is influenced by the long end of the curve, and a Fed rate hike could restore credibility and result in lower long-term borrowing costs (that is, 30-year Treasury yields could drop). Additionally, a rate hold could pressure inflation expectations and push rates even higher at the long end, so TLT’s position is particularly unsettled ahead of the FOMC meeting.
This ad is sent on behalf of Banyan Hill Publishing.
This ad is sent on behalf of Banyan Hill Publishing. . | 
