| The world's most expensive supercomputer is running on trucks.
Not infrastructure. Not a power grid. Trucks. | 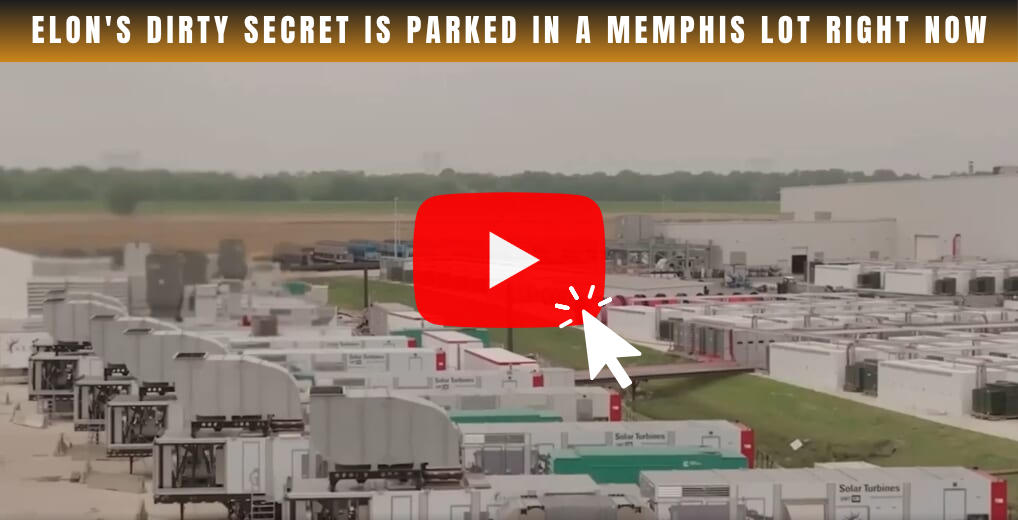 | 46 flatbed gas turbines parked in a Memphis lot are the only thing standing between Elon Musk's $1.77 trillion empire and total blackout. One federal permit. One expiration date. January 2, 2027. When those trucks stop — the $45 billion Anthropic contract dies. The valuation crumbles. The whole empire goes dark overnight. There is one company that builds the permanent fix fast enough to save it. Wall Street hasn't found it yet. Dylan Jovine has. See the name before the gap-up → | | | |
|
|
| Anthropic Is Targeting a $2 Trillion IPO in Mid-October. The Revenue Number Behind That Valuation Is Extraordinary. | | Written by Evan Brooks · September 15, 2026 | |
| The IPO by the Numbers | - Anthropic's IPO timeline has shifted to mid-October at the earliest, with the public S-1 filing expected in late September, per Reuters. The offering — led by Goldman Sachs, JPMorgan, and Morgan Stanley — is targeting a valuation of up to $2 trillion, which would make it the largest IPO in history, surpassing SpaceX's $1.77 trillion June 2026 listing. Anthropic's last private valuation was $965 billion in its May 2026 Series H round, which raised $65 billion.
- Revenue growth has been extraordinary. Anthropic's annualized revenue run rate surpassed $65 billion by end of July 2026, per Bloomberg — up more than 7x from end-of-2025 levels. Q2 2026 revenue exceeded $11.5 billion, compared with $787 million in Q2 2025. Some investors expect annualized revenue to reach $100 billion to $120 billion before year-end. Artemis projects $1 trillion in ARR by 2030, driven by enterprise demand for Claude models.
- The timeline delay stems from Anthropic working to finalize a $15 billion revolving credit facility before the analyst meetings begin — a sequencing requirement that pushed the roadshow back from early September to mid-October. The company is not yet profitable. A $2 trillion valuation implies roughly 10x projected 2028 revenue and approximately 31x the current revenue run rate, per Granite Shares analysis. One investor told the Financial Times that at 800% annual growth, even the low end of reasonable valuation expectations implies a $3 trillion figure.
| | | Why a $2 Trillion Valuation for a Unprofitable Company Is Not Automatically Absurd | | The reflexive response to a $2 trillion valuation for an unprofitable company is to apply the 2021 SPAC-era framework: too high, speculative, lacks earnings anchor. That framework does not fit Anthropic's revenue trajectory. A company that grew from $787 million to over $11.5 billion in quarterly revenue in a single year — and whose annualized run rate may exceed $100 billion before the listing — is not a concept company. It is a business with a measurable revenue trajectory and a compounding growth rate that has been sustained across multiple quarters. The question is not whether the current revenue justifies the valuation — it does not — but whether the projected revenue in 2027 and 2028 justifies it. At a 10x 2028 revenue multiple, which is what Granite Shares calculates the $2 trillion figure implies, the bet is that Anthropic's revenue reaches approximately $200 billion by 2028. That requires the current revenue growth rate — roughly 10x annually — to moderate substantially: from 10x to something closer to 2x to 3x per year between now and 2028. That is the target the market is pricing when it accepts a $2 trillion valuation. It is aggressive but not incoherent. | | The SpaceX comparison is the most instructive pricing reference. SpaceX listed at $1.77 trillion in June 2026 on the strength of Starlink's recurring revenue and the long-duration optionality of its launch business. Starlink's financial profile — recurring subscription revenue with high retention, high margins, and global reach — is the archetype for how public markets price a technology platform with a plausible path to dominant market position. Anthropic's revenue profile resembles Starlink's more than it resembles any traditional software company: Claude API usage is recurring, enterprise contracts are multi-year, and the switching cost for a company that has embedded Claude into its internal workflows is meaningfully high. The market is pricing Anthropic's enterprise API business the way it priced Starlink — as a platform with locked-in recurring revenue, not as a single-product tech company. Whether that pricing is correct depends on whether Anthropic's model quality advantage relative to OpenAI and Google sustains long enough to capture the enterprise contracts that will define its 2028 revenue. That is the variable the public S-1, expected in late September, will need to address. | |
| | Iran bad → oil spikes → you pay more.
Iran deal → oil drops → you "get relief."
Six months later, rinse and repeat.
Think that's an accident?
The same banks advising the White House are trading oil options while the diplomats are still shaking hands.
One man who sat in THOSE rooms — who advised Saudi Arabia AND Kuwait — just went public with the method they use.
Get it before this offer disappears
| | Ad by Omnia Research | | | | |
| The Timing Problem: A $2 Trillion IPO Into a 5% Risk-Free Rate Environment | | The mid-October timing of Anthropic's listing creates a structural tension that does not appear in the revenue multiple analysis. A $2 trillion valuation at a 31x current revenue multiple is priced in an environment where the risk-free rate is below 4%. The 10-year Treasury crossed 5% on September 14. At 5%, the discount rate applied to Anthropic's future cash flows is materially higher than the discount rate embedded in any valuation model built on the pre-September rate environment. A higher discount rate compresses the present value of cash flows that are projected to arrive in 2027 and 2028 — which is precisely where Anthropic's justifying revenue growth is concentrated. The practical implication: if the 10-year holds at or above 5% through the October roadshow, institutional investors who construct DCF models for the offering will apply a higher discount rate than the existing private market valuation assumed. That could push the clearing price below $2 trillion even if the revenue trajectory holds exactly as projected. Value Add VC's IPO analysis noted that a listing near $2 trillion just days before the November midterms adds political noise to an already complex pricing environment. The credit facility sequencing that delayed the timeline was pragmatic — but it moved the listing into a rate environment that is more hostile to long-duration valuation than the August window would have been. | | OpenAI's Absence From Public Markets — and What Anthropic's Listing Prices for Both | | Sam Altman's decision to push OpenAI's IPO to 2027 means that Anthropic's October listing will be the first and only opportunity for public market investors to price a frontier AI safety lab before the next annual cycle of model capability releases. That creates a unique dynamic: Anthropic's public S-1 will disclose revenue, cost structure, and customer concentration data that has been opaque in private markets. That disclosure will immediately allow analysts to reverse-engineer implied assumptions about OpenAI — which had its own private valuation at $852 billion as of March 2026 — and determine whether the OpenAI private market price is consistent with the Anthropic public market price. If Anthropic lists above $2 trillion on strong institutional demand, OpenAI's private market valuation is conservative and Altman's decision to wait becomes an opportunity cost. If Anthropic prices below expectations — say, at $1.5 trillion — because of the rate environment, OpenAI's private valuation looks inflated by comparison. The Anthropic IPO is therefore not just a single company's capital markets event — it is the pricing mechanism for the entire frontier AI lab category at public market multiples. Both the $965 billion OpenAI private valuation and the $852 billion figure will be marked to market against whatever Anthropic's Nasdaq debut produces. That is the largest valuation information event in the AI sector this year, and it arrives six weeks after the most consequential Fed meeting since 2023. | | | | Sources: Granite Shares · Yahoo Finance / Quartz · TechRepublic · Cryptonomist · Time.news · Value Add VC · Startup Hub AI · BitMEX Research · CNBC | |
|
|
© 2026 Alpha One Marketers LLC. All rights reserved. |
|
|
|