The number one mistake new options traders often make 
Optical Cable Corporation Is Starting to Get the Market’s Attention
Written by Thomas Hughes on September 12, 2026
Key Points
- Optical Cable’s third-quarter sales rose 22% as demand strengthened across its enterprise, data center and specialty markets.
- Optical Cable’s backlog reached $13.5 million, while higher production volumes helped drive a sharp improvement in gross profit and earnings.
- Optical Cable has gained visibility through its Russell Microcap Index inclusion and Lightera partnership, but its small size and working-capital needs add risk.
- Special Report: The Rumors About Elon’s Next Move Are Spreading Fast

Optical Cable Corporation (NASDAQ: OCC) is poised for explosive upside as the AI industry drives accelerating demand for its products.
OCC manufactures fiber-optic, copper, and hybrid cabling solutions for data centers, enterprise networks, and government customers.
After a long period of pressure, the stock is rebounding in 2026 and is positioned to reclaim value lost after the DotCom failure.
The takeaway is that this is not a recovery of the old business, but new demand driven by next-gen technologies and AI, which is still in its earliest phases.
Barrick Mining has spent decades building one of the world's great gold districts in Nevada, anchored by Fourmile, Goldrush, and Cortez Hills, a region that could hold as much as 60 million ounces of gold.
Bordering Fourmile and less than a mile from Goldrush sits a little-known explorer now moving from historical data toward active exploration, setting targets and preparing for a maiden drilling program.
With gold trading near record highs, this could be a pivotal stage for an overlooked name in the district. See why this overlooked gold explorer could be entering its most important stage Optical Cable Corporation: A Safe Microcap Play
Optical Cable Corporation is a microcap stock, but unlike most microcaps, it has an established business and, more importantly, cash flow and profits. Q3 results include $24.3 million in revenue, driven by demand across segments, up 22% from last year, and a 570-basis-point improvement in gross margin.
Key details include the backlog, which grew by about 85% year over year, pointing to sustained strength and accelerating momentum in future quarters. Other critical details include significant margin gains linked to revenue leverage, including a 570-basis-point increase in gross margin, and a 10-basis-point reduction in SG&A expenses as a percentage of revenue.
Profitability is real. The company delivered 21 cents in GAAP earnings, up more than 5x from the prior year, and management said strong sales and demand continued into August. The company did not provide guidance, but commentary is optimistic, highlighting improving product demand and expanding global opportunities.
Improving Visibility Underpins Stock Price Action
While analyst coverage and institutional holdings remain limited, improving visibility and market interest are fueling the stock's uptrend. Recent news includes OCC's inclusion in the Russell Microcap Index, a move that not only enhances market awareness but also drives ownership. With approximately $1.5 billion in funds linked to the index, it provides a firm foundation for future price gains.
Additionally, an expanding partnership with Lightera drives gains. Management confirmed the alliance has transitioned from planning to execution, with the first bundled products delivered in Q3. The partnership aligns Lightera’s cable designs with OCC’s bundling, targeting AI designs with a joint go-to-market strategy. Among the benefits for OCC is supply chain stability: Lightera helps insulate the company from industry bottlenecks and shortages by providing cables to bundle.
A little-known Arizona gold explorer just hit 66.2 metres grading 6.57 g/t gold, including 20.7 metres at 18.25 g/t.
After roughly 21,000 metres of drilling, the company is closing in on its first-ever mineral resource estimate, expected in Q3 or Q4 2026.
That estimate could offer the market its first real look at the scale of this emerging gold system. See what could be next for this US gold explorer A Robust Technical Outlook for OCC Stock
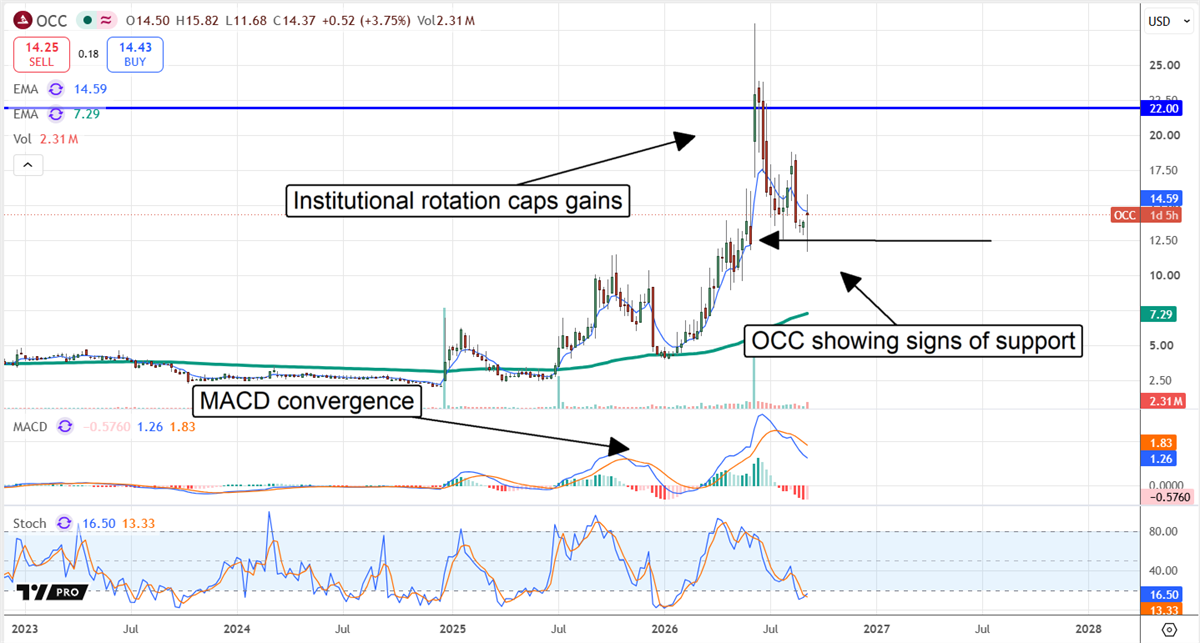
Russell's impact is reflected in institutional data. The group owns a small 13% stake but has been accumulating aggressively over the past few quarters. The only downside is that profit-taking and rotation drove volatility and capped gains in summer 2026, but the technical chart signals point to higher highs later this year in 2026 or early in 2027.
The strongest signals are rising trading volume, which has trended steadily higher since late 2024 when the AI opportunity emerged, and a MACD convergence. MACD convergence can signal improving market momentum, supporting the case for a retest of previous highs if buying pressure continues.
The critical resistance target is near $22.50. It aligns with DotCom-era resistance and marks a significant inflection point for traders. In this scenario, a sustained move above $22.50 signals a buy, with clear upside to about $38. A move to $22.50 is worth about 65% as of early September; a move to $38 adds another 65%-70% in upside.
OCC Has Risks, But the Market Is Wising Up to the Opportunity
The biggest risk for Optical Cable Corporation is its focus on Tier 2 hyperscalers. These are smaller, co-located, AI-focused enterprises and labs, which provide less visibility into future revenue and earnings sustainability. In this environment, revenue and earnings gains can be lumpy and will be reflected in the stock price.
Additionally, the company's lean into inventory has increased its working capital, which creates cash-flow risks. The company will need to convert backlog in a timely fashion to maintain liquidity and financial health. As it stands, the balance sheet is healthy, and leverage is low, but capitalization could be better.
What the market gets wrong about OCC, and what it's starting to realize, is that OCC is no longer a legacy play on commoditized fiber optic cables. The company isn't a standard manufacturer; it produces ruggedized specialty products and has a widening moat built on custom solutions for its Tier 2 clients. Turnkey solutions provide easy, fast deployments for its clients and can deepen customer relationships. More importantly, increased demand and sustainable sales translate directly into bottom-line profitability, which is what counts.
Read this article online ›
Read More
Did you find this article helpful?
 
|